
Canadian Natural Resources and the Long-Life, Low-Decline Argument
The company's asset base needs less sustaining capital than most producers. That is the whole investment thesis, and it is testable.
By Marc Belzile4 min readTranslation: human
本文目前仅提供英文版本。
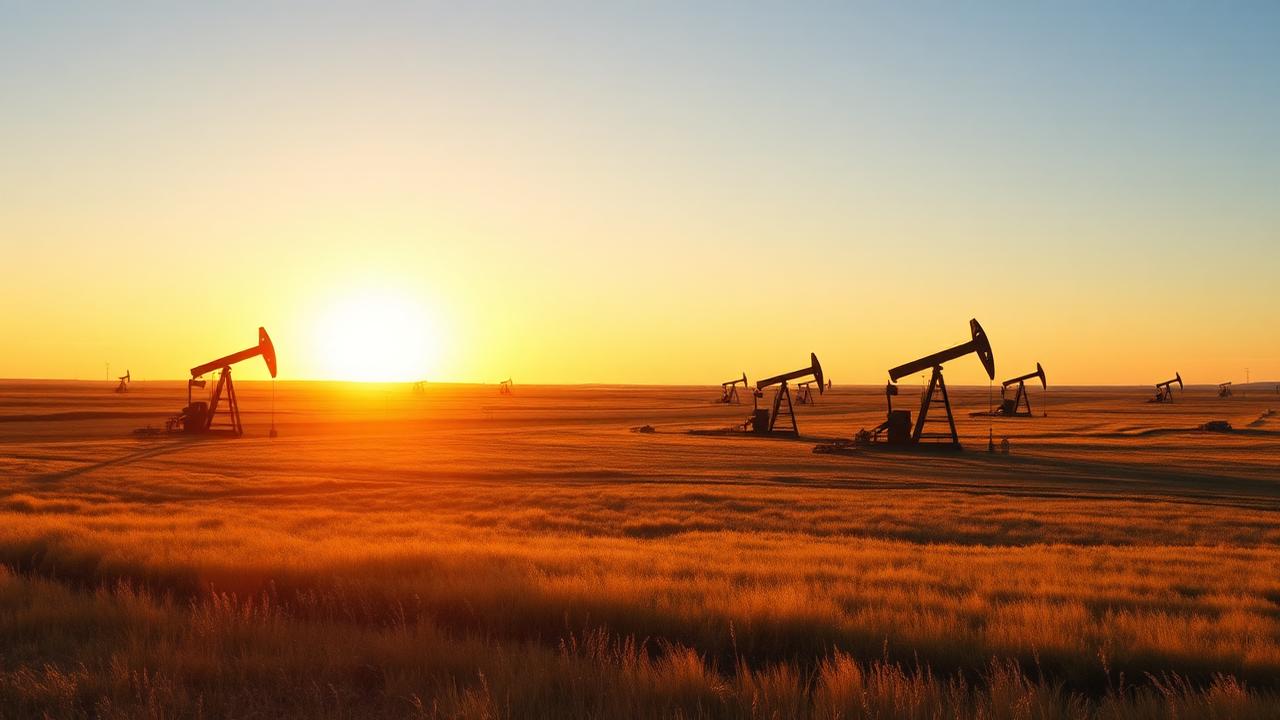
Asset decline rate
Low single digits
Oil sands mining
Key differential
WCS vs WTI
Egress-driven
Cash priority
Base dividend
Then buybacks
Canadian Natural Resources has spent years describing its portfolio as long-life and low-decline. The phrase is marketing until you check it against sustaining capital per barrel, and there it largely holds up. The company's asset base spans oil sands mining, thermal in-situ operations, conventional heavy oil and light oil and natural gas, giving it a diversification within Canadian production that few domestic peers can match. That diversification is central to the long-life argument: it is not one field in decline but a portfolio where different asset classes decline at different rates and can be sequenced against capital availability.
What low decline means in cash terms
Conventional shale assets can decline more than half in the first year, requiring continuous drilling simply to hold production flat. Oil sands mining declines at a small fraction of that. The practical consequence is that a much larger share of operating cash flow is genuinely discretionary rather than committed to a treadmill of replacement drilling. A shale operator that stops reinvesting sees output collapse within a year or two. An oil sands mine that stops investing in expansion can still run for decades off existing infrastructure, with output falling only gradually as mine sequencing and maintenance requirements evolve. This distinction matters most in a downturn, because it determines how much of a company's cash flow can be redirected to debt reduction or shareholder returns without immediately compromising future production. For a long-life low-decline producer, capital allocation becomes a genuine choice rather than a forced expenditure, and that optionality is the core of the valuation argument bulls make for the stock.
The break-even that matters
Management's stated WTI break-even to cover sustaining capital and the base dividend sits well below current strip pricing. Stress-testing that number against a sustained downturn, rather than a two-month dip, is the exercise a serious holder should run. Break-even figures published by producers are typically calculated using current cost structures, current royalty regimes and current currency assumptions, all of which can move against the company simultaneously in a genuine downturn. A weaker Canadian dollar partially offsets lower US-dollar oil prices for a Canadian producer, which is one reason break-evens can look more resilient than a simple oil-price comparison would suggest. But that offset is imperfect, and investors should distinguish between a break-even that covers sustaining capital alone and one that also covers the full dividend, since the two numbers can differ by a meaningful margin and the company's public messaging sometimes blends them.
Where the thesis is vulnerable
Egress remains the structural constraint on Canadian heavy crude. Pipeline availability, the WCS differential and carbon-compliance costs are the three variables that can widen the gap between realised and benchmark pricing regardless of how efficiently the barrels are produced. A low decline rate protects volume; it does not protect price realization. When pipeline capacity is tight relative to production growth across the basin, the WCS-to-WTI differential widens, and every barrel the company produces is worth less at the wellhead even if operating costs have not changed at all. Carbon-compliance costs add a second layer that is likely to grow over time rather than shrink, and the company's ability to manage that cost trajectory through technology investment is a variable that is harder to underwrite than production decline curves, which are largely a function of geology and engineering rather than policy.
Balance sheet discipline as the swing factor
A long-life asset base is only an advantage if the balance sheet can survive the interval between commodity cycles without forced asset sales or dilutive equity issuance. The company's approach to debt reduction during periods of strong cash flow, and its willingness to slow shareholder returns during weaker stretches, is what determines whether the low-decline advantage actually compounds into shareholder value over a full cycle or is instead consumed by leverage taken on during a prior downturn. Investors comparing this company to shale-weighted peers should weigh not just the decline rate difference but the debt capacity each business model can sustainably support.
How this compares with shale-weighted peers
The trade-off against shale-weighted producers is not one-sided. Shale assets can be brought on and shut in quickly, giving those operators more flexibility to respond to short-term price swings, while a long-life asset base is more expensive to build initially and less nimble to throttle. The long-life model rewards patience and penalizes producers who over-lever during a boom; the shale model rewards fast capital redeployment and penalizes producers who cannot access capital markets during a bust. Judging which model performs better over a specific holding period requires taking a view on where in the cycle the commodity currently sits, not simply which decline profile sounds more attractive on paper.
What to watch
Track the reported sustaining capital per barrel over several quarters rather than a single one, since maintenance capital can be deferred temporarily to flatter near-term free cash flow. Watch the WCS differential alongside pipeline utilization data, since a widening differential during a period of otherwise stable production is the clearest sign that egress constraints are reasserting themselves. Finally, monitor the pace of debt reduction during the current part of the cycle, since that pace indicates how much of the long-life advantage management intends to bank for the next downturn rather than distribute immediately.
披露声明
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
接着阅读
英文版: Canadian Natural Resources and the Long-Life, Low-Decline Argument
 Mining & EnergyHomeland Nickel如何为每年约20,000吨精矿签下买方Homeland Nickel于2026年10月1日签署具约束力的协议,由Westwin Elements每年承接俄勒冈州南部Red Flat项目约20,000吨镍精矿;若Westwin对Homeland的初步经济评估感到满意,将出资进行银行级可行性研究。美国林务局于9月接受了Red Flat的声波钻探计划,一笔304万加元的配售也在同月完成。Homeland预计于2027年上半年向Westwin交付两份报告。Élise Galarneau · November 4, 2026 · 7 min
 Mining & EnergyVault Strategic在内华达州:四个月专注于一处钨矿项目2026年7月3日,Vault Strategic Mining放弃另外两项钨矿期权,集中力量开发War Bond。War Bond位于内华达州西部,是1950年代曾经产钨的矿山。此后公司公布了地表采样结果,完成了73.6测线公里的磁法航测,完成150万加元配售,并启动首份NI 43-101技术报告。公司尚未给出报告日期;截至2026年11月30日的六个月财务报表是下一份计划提交的文件。Daniel Okoye · November 4, 2026 · 7 min
 Mining & EnergyQIMC规划横跨三省、总长126.5公里的地震勘探Quebec Innovative Materials已完成新斯科舍省Cumberland县63.7测线公里的地震数据采集。其土壤气、氦、重力和磁法工作以及DDH-26-05钻孔的气体事件都位于同一测网内,目前正在卡尔加里处理。公司还计划与相同承包商在魁北克完成36公里、在安大略完成26.8公里,已完成和计划的覆盖范围合计约126.5测线公里。截至2026年6月30日,公司持有现金1,410万加元。Priya Sandhu · November 3, 2026 · 7 min
Follow this story
Follow CNQ — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
资料来源与参考 (2)
引用本文分析
Please attribute The Maple Markets and link to the original page.
Marc Belzile (April 15, 2026). Canadian Natural Resources and the Long-Life, Low-Decline Argument. The Maple Markets. https://themaplemarkets.ca/zh-hans/newsroom/canadian-natural-resources-and-the-long-life-low-decline-argumenthttps://themaplemarkets.ca/zh-hans/newsroom/canadian-natural-resources-and-the-long-life-low-decline-argument