
Agnico Eagle's Detour Lake Expansion and the Cost of Growth
Expanding Detour Lake is cheaper and lower-risk than a new mine, but underground development and rising strip ratios push sustaining capital per ounce higher. The growth headline and the capital cost behind it need to be read together.
By Daniel Okoye4 min readTranslation: human
Growth type
Brownfield
Lower capital intensity
Hidden cost
Sustaining capital
Rises with underground
Alternative use
Shareholder returns
Comparison required
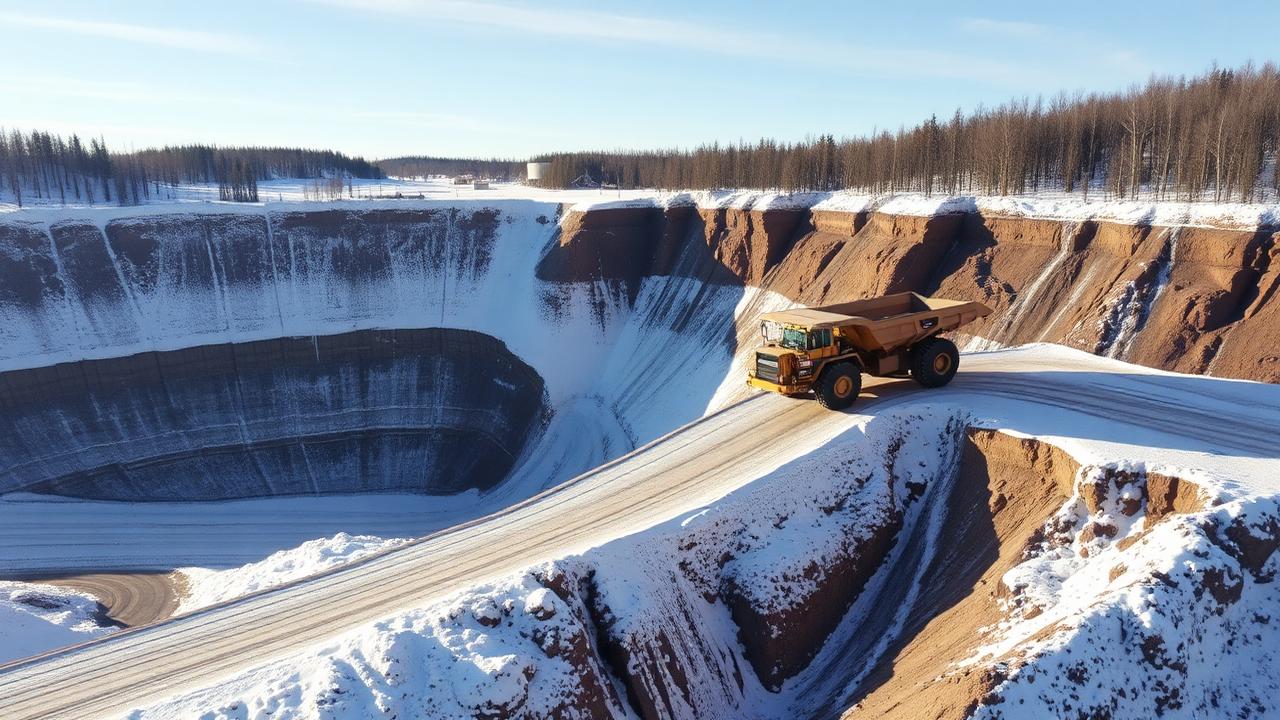
Agnico Eagle's Detour Lake expansion is the clearest illustration in the Canadian gold sector of a rule that gets stated often and applied selectively: it is cheaper to grow an existing mine than to build a new one, but "cheaper" is not the same as "cheap." The project adds incremental ounces to an operation whose pit, mill, tailings capacity, permits and workforce already exist, which is precisely why the market tends to wave brownfield expansions through with less scrutiny than a new build proposal would receive. That leniency is only partly justified.
Why brownfield growth gets the benefit of the doubt
A greenfield mine carries permitting risk that can run years, community and Indigenous consultation processes with uncertain outcomes, and the need to build power, road and water infrastructure from scratch before the first ounce is poured. Detour Lake skips almost all of that. The environmental assessment framework is already established, the local workforce is trained, and the processing circuit exists even if it needs debottlenecking or capacity additions. Capital intensity per incremental ounce is structurally lower than any comparable new development, and the execution timeline is shorter and more predictable. Those are real advantages, and they are the reason producers with mature assets consistently prioritize expansion over exploration-stage acquisitions when the geology allows it.
The cost that the headline growth figure does not show
The complication at Detour Lake, as at many long-life open pits, is that the easiest ounces come first. As a pit matures, expansion increasingly means going underground beneath an operation that was engineered as a surface mine, or pushing the pit deeper and wider at a strip ratio that keeps climbing. Underground development requires different fleets, different ventilation and dewatering infrastructure, and different skill sets than a surface operation was built around, and none of that comes cheap simply because it sits next to an existing plant. The practical effect is that sustaining capital per ounce tends to rise even while total reported production grows. A production chart that only shows tonnes and ounces will look like an unambiguous success. A chart that includes sustaining capital per ounce alongside it tells a more complicated story, because the margin improvement that investors assume comes with higher output is partly consumed by the cost of extracting it.
Why this gets missed in the market's read
Analysts and investors default to production growth as the headline metric because it is the easiest number to compare across companies and across time. Sustaining capital intensity is buried deeper in the disclosure, usually in per-ounce cost guidance that requires cross-referencing against the capital budget rather than reading off a single line. That asymmetry in how easy the two numbers are to find creates a systematic bias toward overrating the value of brownfield expansion, especially late in the life of a pit when the cheap ounces have already been mined. It also means the market tends to re-rate a stock on the growth headline before the market has had time to absorb what the incremental capital spend implies for free cash flow per ounce.
How to judge whether the expansion is worth it
The right framework is not whether Detour Lake can produce more gold — it almost certainly can, given the scale of the reserve base — but whether the marginal ounce, after sustaining capital, generates a return that beats what the company could do with that capital elsewhere. For a company with Agnico Eagle's balance sheet strength and reserve life, funding growth internally rather than through debt or equity issuance is defensible on its face; internally generated cash that is not obviously needed for balance sheet repair is fair game for reinvestment. But defensible is not the same as optimal. The comparison that matters is between the discounted value of ounces that will not be produced for years against the alternative of returning that capital to shareholders through buybacks or dividends today. The further out the ounces sit, and the higher the sustaining capital needed to reach them, the weaker the case for reinvestment relative to distribution, particularly in a commodity where price cycles can turn well before a decade-out mine plan is realized.
What this means for how to read future updates
None of this means the expansion is a mistake. Brownfield growth remains, on almost any measure, the lowest-risk form of production growth available to a major gold producer, and Detour Lake's scale gives Agnico Eagle a reserve base few peers can match. The point is that the growth headline and the capital cost behind it need to be read together, not sequentially, and that a rising production number paired with rising sustaining capital per ounce is a different investment case than a rising production number on its own.
What to watch
Track sustaining capital per ounce at Detour Lake in each quarterly and annual disclosure, not just total production. Watch the strip ratio and any disclosed transition timeline toward underground development, since that is where the cost structure changes most. Compare all-in sustaining cost guidance revisions against production guidance revisions to see whether growth is being delivered at a stable or deteriorating margin. Finally, watch capital allocation commentary on buybacks and dividend growth relative to sustaining and growth capital spend, since that ratio reveals how management itself weighs reinvestment against distribution.
Weiterlesen
Also in English: Agnico Eagle's Detour Lake Expansion and the Cost of Growth
 Mining and ResourcesFür Homeland Nickel läuft die Frist der Forstbehörde, doch die Bohrgenehmigung steht noch ausHomeland Nickel Inc. (TSXV: SHL) teilte am 17. September 2026 mit, der United States Forest Service habe seinen Betriebsplan für ein Sonic-Bohrprogramm in Red Flat, Oregon, angenommen, und die Umwelt- und Kulturgüterprüfung sei weit fortgeschritten, einschließlich abgeschlossener Feldarbeiten. Das Unternehmen hofft, im Oktober zu bohren. Dieselbe Mitteilung wurde am selben Tag erneut versandt, weil ihre Offenlegung zur bezahlten Bewerbung ein Videointerview mit dem Vorstandschef eines anderen Unternehmens beschrieb.Daniel Okoye · 18. September 2026 · 8 min
 Mining and ResourcesAya Gold and Silver hat in Zgounder 3.501 g/t Silber erbohrt und daraus noch nichts verkauftAya Gold & Silver Inc. (TSX: AYA) meldete am 16. September 2026 hochgradige Silberabschnitte nahe der Grube von Zgounder und in der Tiefe, acht Tage nachdem das Unternehmen den Papierwert seines Projekts Boumadine verdoppelt hatte, und fünfzehn Tage nach der Vereinbarung über den Kauf eines Kupfer-Silber-Konzessionspakets. Die Aktie schloss am 17. September bei C$40,24. Das Unternehmen hält US$182,8 Millionen an Barmitteln, und rund 80 Prozent des Metalls in der Boumadine-Studie liegen in der spekulativsten Ressourcenkategorie, die es gibt.Élise Galarneau · 18. September 2026 · 8 min
 Mining and ResourcesFirst Lithium Minerals eröffnet in vier Monaten die dritte Finanzierung, zu einem Preis über dem eigenen SchlusskursFirst Lithium Minerals Corp. (CSE: FLM, FSE: X28) hat am 16. September 2026 eine neue Privatplatzierung nach der Listed-Issuer-Financing-Ausnahme begonnen, die dritte seit Mai. Vollständig gezeichnet brächte sie rund C$5,0 Millionen und 44,6 Millionen neue Aktien gegenüber 112,2 Millionen bereits ausstehenden. Das eigene Angebotsdokument vom Juli bezifferte das Betriebskapital auf rund C$100.000 und trug einen Going-Concern-Hinweis. Die Frankfurter Notierung existiert und machte am 17. September keinen Umsatz.Priya Sandhu · 18. September 2026 · 8 min
Dieser Geschichte folgen
AEM folgen – der nächste Maple-Beitrag zu diesem Unternehmen, dazu der Maple Morning Debrief vor Handelsbeginn.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. Lesen Sie den finanziellen Haftungsausschluss.
Quellen und Verweise (2)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Daniel Okoye (3. Juli 2026). Agnico Eagle's Detour Lake Expansion and the Cost of Growth. The Maple Markets. https://themaplemarkets.ca/de/newsroom/agnico-eagle-s-detour-lake-expansion-and-the-cost-of-growthhttps://themaplemarkets.ca/de/newsroom/agnico-eagle-s-detour-lake-expansion-and-the-cost-of-growth