
Copper's Supply Deficit Is Real, But It Is Not Arriving This Year
Long-term structural demand is genuine. Near-term balances are looser than the electrification narrative implies.
By Daniel Okoye4 min readTranslation: human
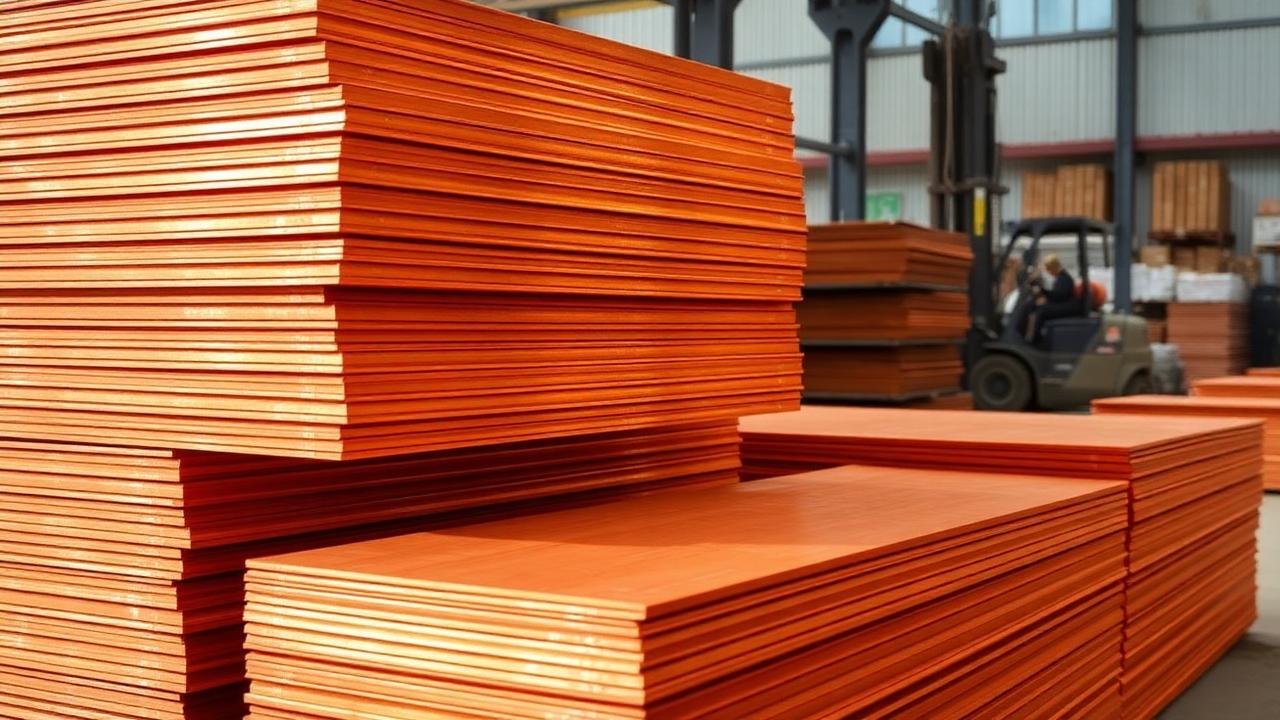
Long-run driver
Electrification
Grid, EVs, data centres
Near-term signal
Exchange inventories
Not drawing down
Fast supply
Scrap
Price responsive
The electrification argument for copper is sound over a decade. Over the next four quarters, the market balance looks considerably more comfortable than that argument suggests, and conflating the two time horizons is the most common mistake made when pricing copper equities and the metal itself. A structural deficit that will plausibly emerge later in the decade does not guarantee that spot prices rise steadily between now and then, and treating a long-run thesis as a near-term trading signal has historically been a costly error in commodity markets.
The long-term case
Grid expansion, electric vehicles and data-centre construction all consume copper intensively. Meanwhile, global average ore grades continue to decline and permitting timelines for new mines routinely exceed a decade. The structural deficit case is well founded. Grid infrastructure alone requires substantially more copper per unit of electricity delivered than fossil-fuel generation when accounting for transmission and distribution build-out, and the pace of electric vehicle adoption adds a second source of incremental demand that did not exist at scale a decade ago. On the supply side, the deposits being discovered and developed today are generally lower grade and more remote than those developed in prior decades, meaning more ore must be moved and processed to produce the same amount of refined metal, and new mine permitting in most major jurisdictions has become slower and more contested over time rather than faster.
The near-term reality
Several large projects are ramping simultaneously and Chinese refined output has been resilient. Visible inventories on the major exchanges have not drawn down in the way a tight market would produce. Scrap supply also responds quickly to high prices. When several major mine expansions or new projects reach commercial production within a similar window, the near-term supply picture can improve meaningfully even while the underlying long-term deficit thesis remains intact, because the projects driving near-term supply growth were approved and funded years earlier under a different set of assumptions. Chinese smelting and refining capacity has continued to expand and operate at high utilization, which has kept refined copper flowing into the market even amid demand uncertainty elsewhere. Exchange inventory levels are one of the more reliable real-time indicators of physical tightness, and a market that is genuinely short of metal typically shows a sustained inventory drawdown rather than the flat-to-rising pattern that has characterized recent periods.
The scrap supply response
Scrap copper is an underappreciated swing factor in the near-term balance. When prices rise, scrap collection and processing economics improve, drawing additional supply into the market relatively quickly compared with the multi-year lead time required to bring new mine supply online. This means the copper market has a built-in near-term shock absorber that does not exist to the same degree for commodities with less developed recycling infrastructure, and it is one reason near-term price spikes driven by temporary supply disruptions tend to be less durable than the structural deficit narrative might otherwise suggest.
The role of demand-side timing risk
The demand side of the long-term thesis also carries timing risk that is worth separating from the supply side. Electric vehicle adoption rates, grid investment cycles and data-centre construction schedules can all shift in timing due to policy changes, financing conditions or macroeconomic slowdowns, even if the long-run direction of travel remains intact. A slower-than-expected pace of adoption in any of these categories over the next several years would push the point at which the structural deficit actually bites further into the future without invalidating the underlying logic of the thesis itself.
How to hold both views
A structural thesis justifies a position; it does not justify ignoring the cycle. Position sizing and entry discipline matter more in copper than in almost any other commodity precisely because the long-run story is so persuasive. Investors convinced by the multi-year deficit argument can express that view through smaller, staged positions that allow for adding exposure if near-term weakness produces better entry prices, rather than committing full-size positions on the assumption that a persuasive long-term narrative should translate into immediate price strength. Separating the investment thesis, which is about the 2030s balance, from the trading thesis, which is about the next several quarters, is the discipline that prevents a sound long-term view from producing poor near-term outcomes.
What to watch
Track exchange inventory levels across the major metal exchanges for signs of a genuine drawdown trend rather than short-term volatility. Watch the pace and completion schedule of major new mine projects currently ramping, since their full run-rate contribution to supply has likely not yet been fully reflected in current output figures. Finally, monitor scrap supply volumes during periods of price strength, since a strong scrap response to higher prices is a signal that near-term tightness is being self-correcting rather than indicative of the structural deficit arriving ahead of schedule.
Weiterlesen
Also in English: Copper's Supply Deficit Is Real, But It Is Not Arriving This Year
 Mining and ResourcesFür Homeland Nickel läuft die Frist der Forstbehörde, doch die Bohrgenehmigung steht noch ausHomeland Nickel Inc. (TSXV: SHL) teilte am 17. September 2026 mit, der United States Forest Service habe seinen Betriebsplan für ein Sonic-Bohrprogramm in Red Flat, Oregon, angenommen, und die Umwelt- und Kulturgüterprüfung sei weit fortgeschritten, einschließlich abgeschlossener Feldarbeiten. Das Unternehmen hofft, im Oktober zu bohren. Dieselbe Mitteilung wurde am selben Tag erneut versandt, weil ihre Offenlegung zur bezahlten Bewerbung ein Videointerview mit dem Vorstandschef eines anderen Unternehmens beschrieb.Daniel Okoye · 18. September 2026 · 8 min
 Mining and ResourcesAya Gold and Silver hat in Zgounder 3.501 g/t Silber erbohrt und daraus noch nichts verkauftAya Gold & Silver Inc. (TSX: AYA) meldete am 16. September 2026 hochgradige Silberabschnitte nahe der Grube von Zgounder und in der Tiefe, acht Tage nachdem das Unternehmen den Papierwert seines Projekts Boumadine verdoppelt hatte, und fünfzehn Tage nach der Vereinbarung über den Kauf eines Kupfer-Silber-Konzessionspakets. Die Aktie schloss am 17. September bei C$40,24. Das Unternehmen hält US$182,8 Millionen an Barmitteln, und rund 80 Prozent des Metalls in der Boumadine-Studie liegen in der spekulativsten Ressourcenkategorie, die es gibt.Élise Galarneau · 18. September 2026 · 8 min
 Mining and ResourcesFirst Lithium Minerals eröffnet in vier Monaten die dritte Finanzierung, zu einem Preis über dem eigenen SchlusskursFirst Lithium Minerals Corp. (CSE: FLM, FSE: X28) hat am 16. September 2026 eine neue Privatplatzierung nach der Listed-Issuer-Financing-Ausnahme begonnen, die dritte seit Mai. Vollständig gezeichnet brächte sie rund C$5,0 Millionen und 44,6 Millionen neue Aktien gegenüber 112,2 Millionen bereits ausstehenden. Das eigene Angebotsdokument vom Juli bezifferte das Betriebskapital auf rund C$100.000 und trug einen Going-Concern-Hinweis. Die Frankfurter Notierung existiert und machte am 17. September keinen Umsatz.Priya Sandhu · 18. September 2026 · 8 min
Den Maple Morning Debrief erhalten
Der gestrige Schluss, die Nacht und worauf Sie vor der Eröffnung achten sollten — bis 6 Uhr ET in Ihrem Postfach. Kostenlos, Abmeldung mit einem Klick.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. Lesen Sie den finanziellen Haftungsausschluss.
Quellen und Verweise (3)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Daniel Okoye (27. Mai 2026). Copper's Supply Deficit Is Real, But It Is Not Arriving This Year. The Maple Markets. https://themaplemarkets.ca/de/newsroom/copper-s-supply-deficit-is-real-but-it-is-not-arriving-this-yearhttps://themaplemarkets.ca/de/newsroom/copper-s-supply-deficit-is-real-but-it-is-not-arriving-this-year