
Ero Copper's Tucumã Ramp-Up Is the Whole Story
A new operation reaching design throughput on schedule changes the cash-flow profile entirely.
By Daniel Okoye3 min readTranslation: human
Cet article n'est offert qu'en anglais pour le moment.
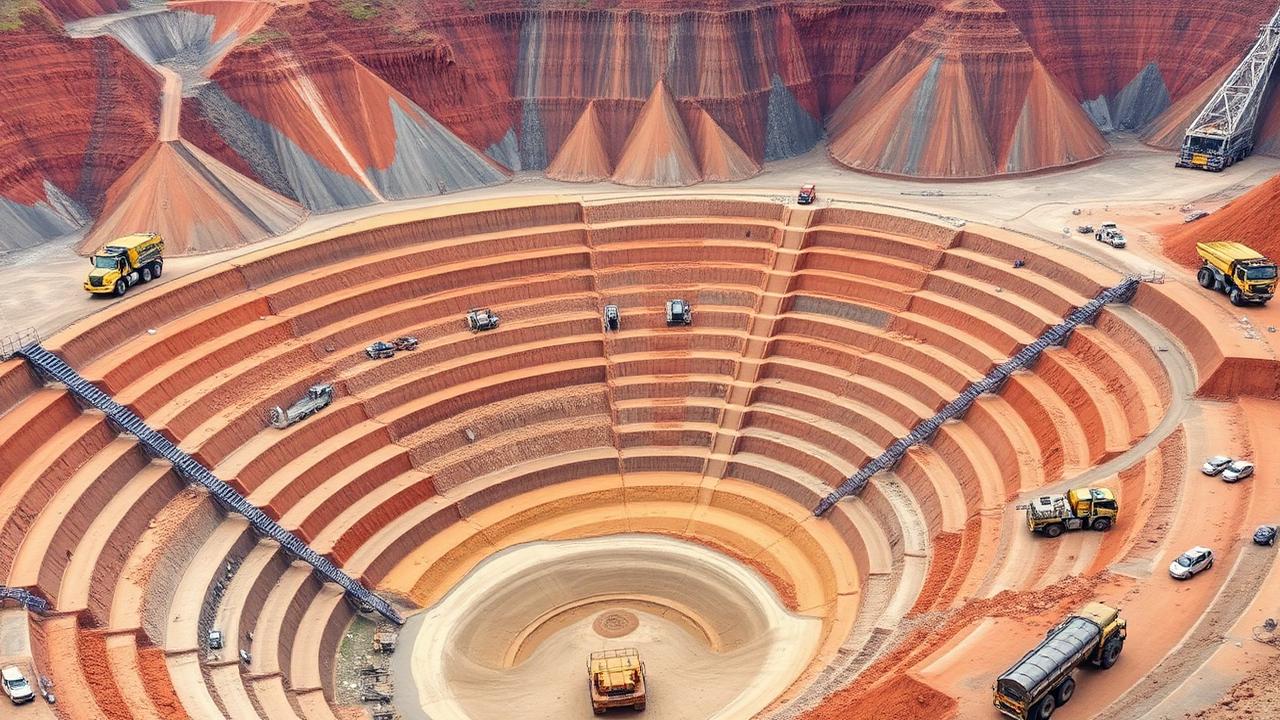
Most common slip
Recovery rates
Persistent problem
Financing risk
Covenant coverage
Debt sized to forecast
Success outcome
Two-asset producer
Discount narrows
For a company moving from developer to multi-asset producer, nothing matters more than whether the new operation reaches nameplate capacity on the promised timeline. Every other line item in the disclosure — cost guidance, exploration spending, balance sheet flexibility — is secondary to that single operational milestone, because it is the event that determines whether the growth thesis behind the investment actually materializes.
Why ramp-ups slip
Commissioning problems concentrate in the processing plant: grinding circuits, flotation recovery and tailings handling. Recovery rates below the design assumption are the most common and most damaging deviation, because they persist rather than resolve. Mechanical issues in a plant, such as a misconfigured crusher or a conveyor breakdown, are usually fixed within weeks. Metallurgical shortfalls are different: if the ore being processed behaves differently from the samples used to design the plant, the flowsheet itself may need to be reworked, which can take quarters rather than weeks and often requires incremental capital to resolve. That is why investors and analysts watch recovery rates specifically, rather than simply tonnes processed, as the leading indicator of ramp-up health.
The financing consequence
Development is typically funded with debt sized against a production forecast. A ramp-up delay of a few quarters can turn a comfortable coverage ratio into a covenant negotiation, which is why the market punishes delays disproportionately. Lenders structure covenants around a base-case production and cost forecast, with limited tolerance for extended underperformance. When a ramp-up runs behind schedule, the shortfall in cash flow relative to what was modeled can quickly erode the cushion built into those covenants, forcing the company into discussions with lenders over waivers, amended terms or additional equity, any of which can be dilutive or costly. This is a large part of why ramp-up delays tend to produce an outsized negative market reaction relative to the size of the shortfall itself — the market is pricing not just the lost production, but the increased financing risk.
Distinguishing a delay from a failure
Not every ramp-up slip is equivalent. A short delay tied to a specific, identifiable mechanical issue with a clear fix is qualitatively different from a persistent recovery shortfall with no clear resolution path. Investors should look for management's ability to isolate the root cause and to point to a specific remediation plan with a defined timeline, since vague or repeatedly revised guidance is usually a signal that the underlying issue is not yet understood. A company that provides granular, plant-level detail — throughput, grade, recovery, by circuit — during a ramp-up is giving investors the tools to judge progress for themselves, which is itself a useful signal about management credibility.
What success delivers
Reaching design throughput converts the company from one asset to two, materially reducing the concentration discount and generating free cash flow that funds exploration without dilution. A single-asset producer carries a valuation discount tied to the operational and geological risk of relying on one mine; successfully commissioning a second asset diversifies that risk and typically re-rates the shares toward multi-asset peers. It also changes the capital allocation picture entirely: instead of needing external financing to fund growth, free cash flow from two producing assets can support exploration on other targets and further development, compounding the value of the exploration portfolio without diluting existing shareholders.
What to watch
Track quarterly throughput and, most importantly, recovery rates against the original design assumptions, along with any revisions to production or cost guidance. Watch covenant compliance and available liquidity relative to the financing structure, and monitor management's disclosed root-cause analysis and remediation timeline for any reported shortfalls, since the specificity of that commentary is itself an indicator of how close the operation is to resolving its issues.
Divulgation
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
À lire ensuite
Aussi en anglais: Ero Copper's Tucumã Ramp-Up Is the Whole Story
 Mining & EnergyPourquoi Lundin Mining a abaissé sa prévision de production de cuivre pour 2026Le troisième trimestre de Lundin Mining, publié le 4 novembre 2026, a combiné une production de cuivre en recul à Caserones, au Chili, et des revenus de US$1,109.2 millions à un prix réalisé du cuivre record. La société a ramené sa prévision de cuivre pour 2026 à 285,000 à 310,000 tonnes, maintenu sa prévision de coûts, déclaré son dividende régulier de C$0.0275 et déclaré une trésorerie nette de US$237.0 millions au 30 septembre. L'action a clôturé à C$28.05 le 5 novembre, en baisse de 11.43 pour cent.Daniel Okoye · 5 novembre 2026 · 8 min
 Contenu commanditéMining & Energy19.9 millions d'unités admissibles alors que Copper One se rend à MunichCopper One Resources a déposé le 3 novembre 2026 un supplément de prospectus qui admet au placement 19,889,750 unités issues de son financement par bons de souscription spéciaux de C$7,955,900, ainsi qu'une notice annuelle volontaire, quelques jours après que son premier sondage de la phase 2 à Majuba Hill, au Nevada, eut révélé du cuivre natif identifié visuellement. Les résultats d'analyse en laboratoire sont attendus, et la société fait une présentation à Munich les 6 et 7 novembre.Daryl Frètu Von · 5 novembre 2026 · 8 min
 Mining & EnergyUS$852 millions de flux de trésorerie disponibles : le troisième trimestre d'Agnico EagleAgnico Eagle a déclaré 814,012 onces d'or et US$852 millions de flux de trésorerie disponibles pour le troisième trimestre de 2026, a terminé septembre avec US$3.6 milliards en trésorerie pour une dette de US$197 millions, et a maintenu sa fourchette de prévisions pour 2026 tout en indiquant que la production se situera près de la borne inférieure de la fourchette après un mouvement de roche dans la fosse Barnat. L'action a progressé avec celles des producteurs d'or canadiens le 4 novembre.Élise Galarneau · 5 novembre 2026 · 7 min
Follow this story
Follow ERO — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Sources et références (2)
Citer cette analyse
Please attribute The Maple Markets and link to the original page.
Daniel Okoye (July 27, 2026). Ero Copper's Tucumã Ramp-Up Is the Whole Story. The Maple Markets. https://themaplemarkets.ca/fr/newsroom/ero-copper-s-tucuma-ramp-up-is-the-whole-storyhttps://themaplemarkets.ca/fr/newsroom/ero-copper-s-tucuma-ramp-up-is-the-whole-story