
Ero Copper's Tucumã Ramp-Up Is the Whole Story
A new operation reaching design throughput on schedule changes the cash-flow profile entirely.
By Daniel Okoye3 min readTranslation: human
Most common slip
Recovery rates
Persistent problem
Financing risk
Covenant coverage
Debt sized to forecast
Success outcome
Two-asset producer
Discount narrows
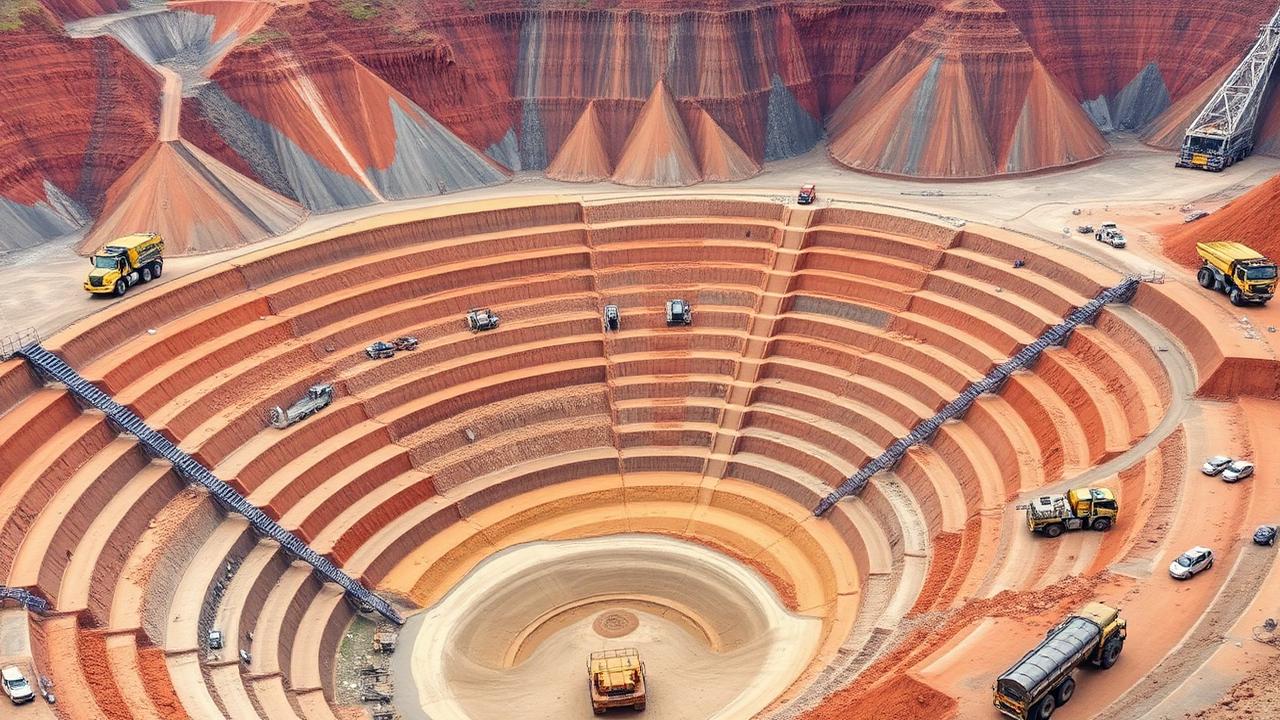
For a company moving from developer to multi-asset producer, nothing matters more than whether the new operation reaches nameplate capacity on the promised timeline. Every other line item in the disclosure — cost guidance, exploration spending, balance sheet flexibility — is secondary to that single operational milestone, because it is the event that determines whether the growth thesis behind the investment actually materializes.
Why ramp-ups slip
Commissioning problems concentrate in the processing plant: grinding circuits, flotation recovery and tailings handling. Recovery rates below the design assumption are the most common and most damaging deviation, because they persist rather than resolve. Mechanical issues in a plant, such as a misconfigured crusher or a conveyor breakdown, are usually fixed within weeks. Metallurgical shortfalls are different: if the ore being processed behaves differently from the samples used to design the plant, the flowsheet itself may need to be reworked, which can take quarters rather than weeks and often requires incremental capital to resolve. That is why investors and analysts watch recovery rates specifically, rather than simply tonnes processed, as the leading indicator of ramp-up health.
The financing consequence
Development is typically funded with debt sized against a production forecast. A ramp-up delay of a few quarters can turn a comfortable coverage ratio into a covenant negotiation, which is why the market punishes delays disproportionately. Lenders structure covenants around a base-case production and cost forecast, with limited tolerance for extended underperformance. When a ramp-up runs behind schedule, the shortfall in cash flow relative to what was modeled can quickly erode the cushion built into those covenants, forcing the company into discussions with lenders over waivers, amended terms or additional equity, any of which can be dilutive or costly. This is a large part of why ramp-up delays tend to produce an outsized negative market reaction relative to the size of the shortfall itself — the market is pricing not just the lost production, but the increased financing risk.
Distinguishing a delay from a failure
Not every ramp-up slip is equivalent. A short delay tied to a specific, identifiable mechanical issue with a clear fix is qualitatively different from a persistent recovery shortfall with no clear resolution path. Investors should look for management's ability to isolate the root cause and to point to a specific remediation plan with a defined timeline, since vague or repeatedly revised guidance is usually a signal that the underlying issue is not yet understood. A company that provides granular, plant-level detail — throughput, grade, recovery, by circuit — during a ramp-up is giving investors the tools to judge progress for themselves, which is itself a useful signal about management credibility.
What success delivers
Reaching design throughput converts the company from one asset to two, materially reducing the concentration discount and generating free cash flow that funds exploration without dilution. A single-asset producer carries a valuation discount tied to the operational and geological risk of relying on one mine; successfully commissioning a second asset diversifies that risk and typically re-rates the shares toward multi-asset peers. It also changes the capital allocation picture entirely: instead of needing external financing to fund growth, free cash flow from two producing assets can support exploration on other targets and further development, compounding the value of the exploration portfolio without diluting existing shareholders.
What to watch
Track quarterly throughput and, most importantly, recovery rates against the original design assumptions, along with any revisions to production or cost guidance. Watch covenant compliance and available liquidity relative to the financing structure, and monitor management's disclosed root-cause analysis and remediation timeline for any reported shortfalls, since the specificity of that commentary is itself an indicator of how close the operation is to resolving its issues.
Weiterlesen
Also in English: Ero Copper's Tucumã Ramp-Up Is the Whole Story
 Mining and ResourcesFür Homeland Nickel läuft die Frist der Forstbehörde, doch die Bohrgenehmigung steht noch ausHomeland Nickel Inc. (TSXV: SHL) teilte am 17. September 2026 mit, der United States Forest Service habe seinen Betriebsplan für ein Sonic-Bohrprogramm in Red Flat, Oregon, angenommen, und die Umwelt- und Kulturgüterprüfung sei weit fortgeschritten, einschließlich abgeschlossener Feldarbeiten. Das Unternehmen hofft, im Oktober zu bohren. Dieselbe Mitteilung wurde am selben Tag erneut versandt, weil ihre Offenlegung zur bezahlten Bewerbung ein Videointerview mit dem Vorstandschef eines anderen Unternehmens beschrieb.Daniel Okoye · 18. September 2026 · 8 min
 Mining and ResourcesAya Gold and Silver hat in Zgounder 3.501 g/t Silber erbohrt und daraus noch nichts verkauftAya Gold & Silver Inc. (TSX: AYA) meldete am 16. September 2026 hochgradige Silberabschnitte nahe der Grube von Zgounder und in der Tiefe, acht Tage nachdem das Unternehmen den Papierwert seines Projekts Boumadine verdoppelt hatte, und fünfzehn Tage nach der Vereinbarung über den Kauf eines Kupfer-Silber-Konzessionspakets. Die Aktie schloss am 17. September bei C$40,24. Das Unternehmen hält US$182,8 Millionen an Barmitteln, und rund 80 Prozent des Metalls in der Boumadine-Studie liegen in der spekulativsten Ressourcenkategorie, die es gibt.Élise Galarneau · 18. September 2026 · 8 min
 Mining and ResourcesFirst Lithium Minerals eröffnet in vier Monaten die dritte Finanzierung, zu einem Preis über dem eigenen SchlusskursFirst Lithium Minerals Corp. (CSE: FLM, FSE: X28) hat am 16. September 2026 eine neue Privatplatzierung nach der Listed-Issuer-Financing-Ausnahme begonnen, die dritte seit Mai. Vollständig gezeichnet brächte sie rund C$5,0 Millionen und 44,6 Millionen neue Aktien gegenüber 112,2 Millionen bereits ausstehenden. Das eigene Angebotsdokument vom Juli bezifferte das Betriebskapital auf rund C$100.000 und trug einen Going-Concern-Hinweis. Die Frankfurter Notierung existiert und machte am 17. September keinen Umsatz.Priya Sandhu · 18. September 2026 · 8 min
Dieser Geschichte folgen
ERO folgen – der nächste Maple-Beitrag zu diesem Unternehmen, dazu der Maple Morning Debrief vor Handelsbeginn.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. Lesen Sie den finanziellen Haftungsausschluss.
Quellen und Verweise (2)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Daniel Okoye (27. Juli 2026). Ero Copper's Tucumã Ramp-Up Is the Whole Story. The Maple Markets. https://themaplemarkets.ca/de/newsroom/ero-copper-s-tucuma-ramp-up-is-the-whole-storyhttps://themaplemarkets.ca/de/newsroom/ero-copper-s-tucuma-ramp-up-is-the-whole-story