
Nutrien and the Potash Price Floor Nobody Can Agree On
Potash prices are set through negotiated annual contracts rather than a continuous market, which is why analysts disagree so sharply on where the price floor actually sits. This piece looks at Nutrien's low-cost and retail-diversified position within that unusually concentrated market structure.
By Daniel Okoye3 min readTranslation: human
本文目前仅提供英文版本。
Market structure
Concentrated
Few producers, few buyers
Nutrien differentiator
Retail segment
Less commodity-correlated
Swing factor
Sanctioned supply
Route dependent
Annual potash contract negotiations with the largest importing buyers set a reference price that ripples through the entire global fertiliser complex, and this year's settlement again arrived later than the market expected. The delay itself is informative: it signals that neither side had an obvious incentive to move first, and it is a reminder that potash pricing is negotiated, not discovered in a continuous market the way most commodities are.
A concentrated market
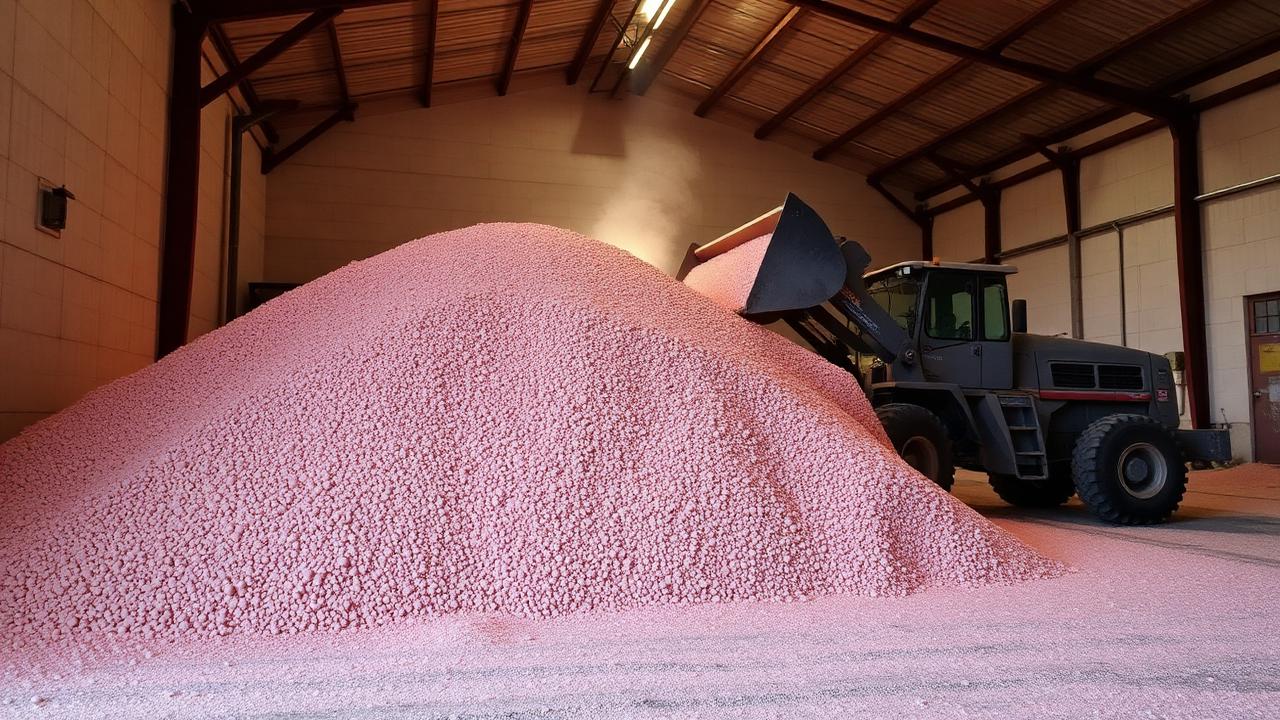
Global potash supply is dominated by a small number of producers in Canada, Russia and Belarus. Demand is heavily influenced by two very large buyers. The result is a market where negotiated settlements matter more than marginal cost curves. This structure is unusual among bulk commodities. In most mined or agricultural commodities, price discovery happens through exchanges or a large number of bilateral spot transactions, and marginal cost of the highest-cost producer needed to meet demand sets a floor. Potash instead moves through periodic contract negotiations between a handful of producers and a handful of large state-linked or state-influenced buyers, which means price can be sticky in either direction for longer than a purely competitive market would allow, and can move in large discrete steps when a settlement is finally reached.
Why nobody agrees on the floor
Because price is set through negotiation rather than a continuous market, there is no single agreed marginal cost of production that acts as an obvious floor the way it might in oil or copper. Estimates of where the floor should sit differ depending on assumptions about Belarusian and Russian output reaching market despite sanctions-related friction, the willingness of Canadian producers to curtail volume rather than compete on price, and how much pricing power the largest buyers retain given how concentrated demand is. Each of these assumptions is legitimately contestable, which is why analyst views on the sustainable floor price vary so widely, and why the annual settlement is watched so closely as the actual revealed answer rather than a modelled one.
Nutrien's position
Low-cost Saskatchewan production and integrated retail distribution give Nutrien a different exposure than a pure producer. The retail segment provides earnings that are less correlated to the commodity price, though it carries its own working-capital cycle. The low-cost Saskatchewan resource base means Nutrien can remain profitable at potash prices that would pressure higher-cost producers, giving it more flexibility to hold or cede volume during periods of price weakness rather than being forced to sell into a weak market simply to cover costs. The retail arm, which sells crop inputs and services directly to growers, does not eliminate commodity exposure but it diversifies the earnings stream across a business with different seasonality and different competitive dynamics than the potash mining operation itself.
The Belarus and Russia variable
Sanctions on Belarusian potash exports, and the logistics constraints that come with rerouting volumes through different ports and rail networks, have been a persistent source of supply-side uncertainty. The pace at which that volume finds its way back to end markets, whether through alternative logistics or through demand from buyers less affected by sanctions regimes, is one of the largest single variables in any potash supply forecast. It is also one of the hardest to forecast precisely, because it depends on geopolitical decisions and enforcement patterns rather than on production economics.
Demand-side variables
Application rates in large consuming regions such as Brazil and Southeast Asia depend on grower economics, which in turn depend on crop prices, weather, and the availability of financing for input purchases. In a year of weak crop prices, growers can and do defer potash application without materially damaging soil in the short term, which makes potash demand more elastic in the near term than many other agricultural inputs. That elasticity is part of why the demand side of the price-floor debate is as contested as the supply side.
What to watch
Track the timing and level of the next annual contract settlements with major importing buyers, since these are the clearest revealed data point on where negotiated price actually lands. Watch disclosed shipment and logistics data on Belarusian and Russian export volumes for evidence of sanctions-related supply actually reaching market. Monitor Nutrien's realized potash price against its production cost guidance, and separately track retail segment margins and working capital, since that segment's performance is the clearest read on how much true diversification the integrated model provides.
披露声明
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
接着阅读
英文版: Nutrien and the Potash Price Floor Nobody Can Agree On
 Mining & EnergyVault Strategic在内华达州:四个月专注于一处钨矿项目2026年7月3日,Vault Strategic Mining放弃另外两项钨矿期权,集中力量开发War Bond。War Bond位于内华达州西部,是1950年代曾经产钨的矿山。此后公司公布了地表采样结果,完成了73.6测线公里的磁法航测,完成150万加元配售,并启动首份NI 43-101技术报告。公司尚未给出报告日期;截至2026年11月30日的六个月财务报表是下一份计划提交的文件。Daniel Okoye · November 4, 2026 · 7 min
 Mining & EnergyQIMC规划横跨三省、总长126.5公里的地震勘探Quebec Innovative Materials已完成新斯科舍省Cumberland县63.7测线公里的地震数据采集。其土壤气、氦、重力和磁法工作以及DDH-26-05钻孔的气体事件都位于同一测网内,目前正在卡尔加里处理。公司还计划与相同承包商在魁北克完成36公里、在安大略完成26.8公里,已完成和计划的覆盖范围合计约126.5测线公里。截至2026年6月30日,公司持有现金1,410万加元。Priya Sandhu · November 3, 2026 · 7 min
 TechnologyReklaim连续第三个季度盈利,股价上涨45%Reklaim Ltd.于2026年11月3日公布,截至9月30日的季度营收同比增长近两倍,达到316万加元,净利润127万加元,为连续第三个盈利季度。该股在多伦多创业板收于C$0.40,上涨45%,成交193万股。公司当季回购510万股;前一天,公司提议允许C$500,000可转换债券的持有人按现行C$0.105的价格提前转股,此事尚待多伦多创业板批准。Marc Belzile · November 3, 2026 · 6 min
Follow this story
Follow NTR — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
资料来源与参考 (2)
引用本文分析
Please attribute The Maple Markets and link to the original page.
Daniel Okoye (May 18, 2026). Nutrien and the Potash Price Floor Nobody Can Agree On. The Maple Markets. https://themaplemarkets.ca/zh-hans/newsroom/nutrien-and-the-potash-price-floor-nobody-can-agree-onhttps://themaplemarkets.ca/zh-hans/newsroom/nutrien-and-the-potash-price-floor-nobody-can-agree-on