
Nutrien and the Potash Price Floor Nobody Can Agree On
Potash prices are set through negotiated annual contracts rather than a continuous market, which is why analysts disagree so sharply on where the price floor actually sits. This piece looks at Nutrien's low-cost and retail-diversified position within that unusually concentrated market structure.
By Daniel Okoye3 min readTranslation: human
Dieser Artikel ist derzeit nur auf Englisch verfügbar.
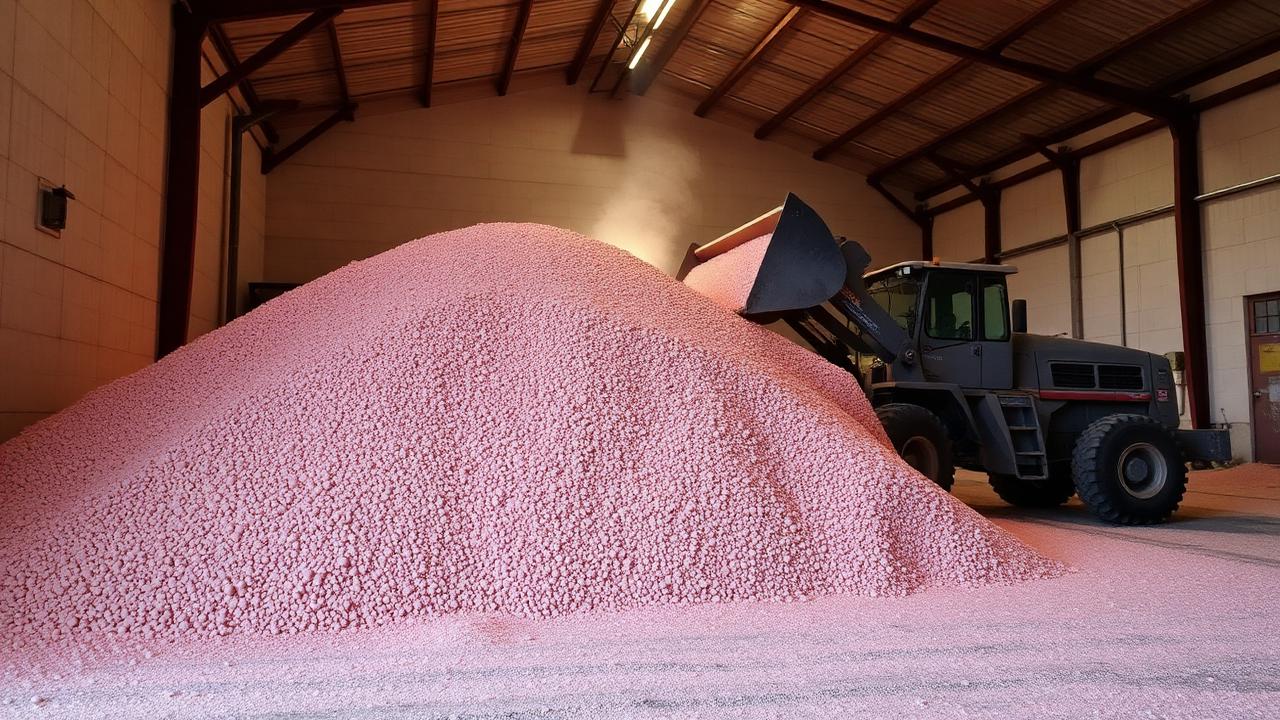
Market structure
Concentrated
Few producers, few buyers
Nutrien differentiator
Retail segment
Less commodity-correlated
Swing factor
Sanctioned supply
Route dependent
Annual potash contract negotiations with the largest importing buyers set a reference price that ripples through the entire global fertiliser complex, and this year's settlement again arrived later than the market expected. The delay itself is informative: it signals that neither side had an obvious incentive to move first, and it is a reminder that potash pricing is negotiated, not discovered in a continuous market the way most commodities are.
A concentrated market
Global potash supply is dominated by a small number of producers in Canada, Russia and Belarus. Demand is heavily influenced by two very large buyers. The result is a market where negotiated settlements matter more than marginal cost curves. This structure is unusual among bulk commodities. In most mined or agricultural commodities, price discovery happens through exchanges or a large number of bilateral spot transactions, and marginal cost of the highest-cost producer needed to meet demand sets a floor. Potash instead moves through periodic contract negotiations between a handful of producers and a handful of large state-linked or state-influenced buyers, which means price can be sticky in either direction for longer than a purely competitive market would allow, and can move in large discrete steps when a settlement is finally reached.
Why nobody agrees on the floor
Because price is set through negotiation rather than a continuous market, there is no single agreed marginal cost of production that acts as an obvious floor the way it might in oil or copper. Estimates of where the floor should sit differ depending on assumptions about Belarusian and Russian output reaching market despite sanctions-related friction, the willingness of Canadian producers to curtail volume rather than compete on price, and how much pricing power the largest buyers retain given how concentrated demand is. Each of these assumptions is legitimately contestable, which is why analyst views on the sustainable floor price vary so widely, and why the annual settlement is watched so closely as the actual revealed answer rather than a modelled one.
Nutrien's position
Low-cost Saskatchewan production and integrated retail distribution give Nutrien a different exposure than a pure producer. The retail segment provides earnings that are less correlated to the commodity price, though it carries its own working-capital cycle. The low-cost Saskatchewan resource base means Nutrien can remain profitable at potash prices that would pressure higher-cost producers, giving it more flexibility to hold or cede volume during periods of price weakness rather than being forced to sell into a weak market simply to cover costs. The retail arm, which sells crop inputs and services directly to growers, does not eliminate commodity exposure but it diversifies the earnings stream across a business with different seasonality and different competitive dynamics than the potash mining operation itself.
The Belarus and Russia variable
Sanctions on Belarusian potash exports, and the logistics constraints that come with rerouting volumes through different ports and rail networks, have been a persistent source of supply-side uncertainty. The pace at which that volume finds its way back to end markets, whether through alternative logistics or through demand from buyers less affected by sanctions regimes, is one of the largest single variables in any potash supply forecast. It is also one of the hardest to forecast precisely, because it depends on geopolitical decisions and enforcement patterns rather than on production economics.
Demand-side variables
Application rates in large consuming regions such as Brazil and Southeast Asia depend on grower economics, which in turn depend on crop prices, weather, and the availability of financing for input purchases. In a year of weak crop prices, growers can and do defer potash application without materially damaging soil in the short term, which makes potash demand more elastic in the near term than many other agricultural inputs. That elasticity is part of why the demand side of the price-floor debate is as contested as the supply side.
What to watch
Track the timing and level of the next annual contract settlements with major importing buyers, since these are the clearest revealed data point on where negotiated price actually lands. Watch disclosed shipment and logistics data on Belarusian and Russian export volumes for evidence of sanctions-related supply actually reaching market. Monitor Nutrien's realized potash price against its production cost guidance, and separately track retail segment margins and working capital, since that segment's performance is the clearest read on how much true diversification the integrated model provides.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
Weiterlesen
Also in English: Nutrien and the Potash Price Floor Nobody Can Agree On
 Mining & EnergyIvanhoe Mines berichtet am Dienstag über ein Kupferquartal mit 76,401 TonnenIvanhoe Mines veröffentlicht seine Finanzergebnisse für das dritte Quartal 2026 nach Börsenschluss am 3. November und veranstaltet die Telefonkonferenz am 4. November. Die Produktion ist bereits öffentlich: 76,401 Tonnen Kupfer aus Kamoa-Kakula, ein Rekord von 77,147 Tonnen Zink aus Kipushi und eine bestätigte Prognose. Die Ergebnisse ergänzen Gewinne, Kosten und Bilanz hinter diesen Tonnen; die Aktie schloss am 2. November bei C$9.00.Élise Galarneau · 3. November 2026 · 6 min
 Mining & EnergyMyriad Uranium schließt den Erwerb des 55,000 Hektar großen Projekts Los Altares in Argentinien abMyriad Uranium hat am 2. November 2026 den Erwerb des Projekts Los Altares im Zentrum der argentinischen Provinz Chubut abgeschlossen und übernimmt 100 Prozent von rund 55,000 Hektar neben dem bekanntesten Urandistrikt Argentiniens, für C$300,000 in bar, 1,571,268 Aktien und eine Lizenzgebühr von 2 Prozent. Das Unternehmen will die rund 12,500 Meter historischer Bohrungen zusammenstellen und den Sandstein auf In-situ-Laugung prüfen; eine Ressource wurde für das Projekt nicht geschätzt.Daniel Okoye · 3. November 2026 · 6 min
 Mining & EnergyUranium One startet nach Genehmigung erstes Uranprogramm in ParaguayUranium One Mining Corp. (CSE: UUU) verfügt über die Prospektionsgenehmigung des paraguayischen Bergbauministeriums und teilte am 2. November 2026 mit, dass das erste Explorationsprogramm des Unternehmens auf dem rund 90,000 Hektar großen Uranprojekt Yuty Prometeo läuft. Der Prometeo-Block grenzt direkt an das Yuty-Projekt der Uranium Energy Corp., eine definierte Ressource, die sich laut UEC nach vorläufigen Studien für die In-situ-Gewinnung eignet. Historische Anschutz-Aufzeichnungen zu Prometeo nennen 0.05 bis 0.10 Prozent U3O8 über 107 Meter, und San Jose kommt als zweites, größeres Zielgebiet hinzu.Élise Galarneau · 2. November 2026 · 8 min
Dieser Geschichte folgen
NTR folgen – der nächste Maple-Beitrag zu diesem Unternehmen, dazu der Maple Morning Debrief vor Handelsbeginn.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Quellen und Verweise (2)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Daniel Okoye (18. Mai 2026). Nutrien and the Potash Price Floor Nobody Can Agree On. The Maple Markets. https://themaplemarkets.ca/de/newsroom/nutrien-and-the-potash-price-floor-nobody-can-agree-onhttps://themaplemarkets.ca/de/newsroom/nutrien-and-the-potash-price-floor-nobody-can-agree-on