
Descartes Systems and the Case for Unglamorous Software
Logistics software is dull, sticky and priced accordingly. The switching costs are the moat.
By Priya Sandhu4 min readTranslation: human
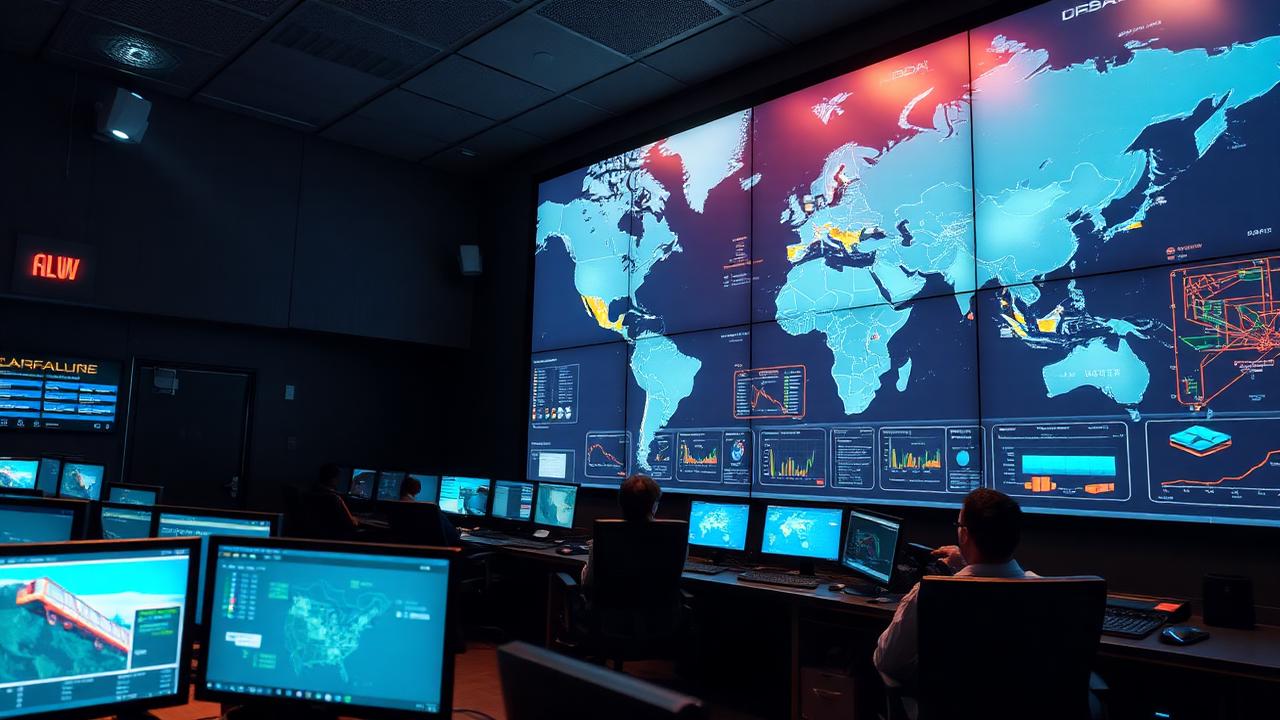
Moat
Switching costs
Compliance re-certification
Cash conversion
High
Low capital intensity
Cyclical exposure
Trade volumes
Transaction revenue
Descartes sells software that routes freight, files customs declarations and manages compliance. Nobody writes breathless coverage about it, which is part of why it has compounded quietly for two decades. The business sits inside a category investors tend to underrate: infrastructure software that customers cannot easily rip out, serving an industry — global trade logistics — that never stops needing to move goods across borders.
Where the stickiness comes from
Once a logistics network is integrated into a customer's operations and connected to customs authorities, replacing it means re-certifying compliance workflows across multiple jurisdictions. The cost of switching is measured in operational risk, not licence fees. A shipper, freight forwarder or customs broker that has built its processes around a given platform faces the prospect of re-testing every regulatory interface, retraining staff and risking shipment delays during any transition. That asymmetry between the modest cost of staying and the outsized cost of leaving is the foundation of the entire investment case. It is also why the company can operate a large network of customers without needing to compete primarily on price: the value proposition is continuity and certainty, not the cheapest quote.
Growth mechanics
Organic growth is steady rather than spectacular, supplemented by regular tuck-in acquisitions of adjacent capability. Free cash flow conversion is high because the capital requirements of the business are modest. This combination — a network-effect core business layered with disciplined, small acquisitions — is a deliberate strategy rather than an accident. Each acquisition typically adds a capability (a new geography, a new mode of transport, a new regulatory function) that becomes more valuable once cross-sold into the existing customer base than it was as a standalone business. Because the balance sheet is not capital-intensive, the company can fund this acquisition programme largely from its own cash generation, which limits dilution and keeps leverage low relative to peers that rely more heavily on debt-funded consolidation.
Reading the growth quality
Investors assessing this kind of business need to separate the transaction-based, volume-linked revenue from the subscription and platform-fee revenue that renews independently of trade activity. The former rises and falls with global shipping volumes; the latter is closer to a fixed, contracted stream. The blend between the two determines how much of any reported revenue growth is durable versus cyclical. A quarter of strong growth driven mostly by elevated freight volumes reads very differently from the same headline growth rate achieved through net new customer wins or successful cross-selling of acquired modules. Disclosure around customer retention, net revenue retention and the split between recurring and transactional revenue is therefore more informative than the headline growth number alone.
The risk
Trade volumes drive transaction-based revenue. A sustained contraction in cross-border shipping reduces the variable component. Valuation also leaves limited room for execution disappointment. Because the market has come to trust the compounding narrative, the shares tend to carry a premium multiple relative to the broader software sector, which means the stock is more sensitive than most to any sign that acquisition integration is slipping, that organic growth is decelerating structurally rather than cyclically, or that a major customs or trade-policy shift is disrupting the volume base the platform depends on. A second, less obvious risk is regulatory: because the software's value is partly derived from interfacing with government customs systems, changes in how those systems operate, or moves by governments to build competing in-house capability, could erode a portion of the switching-cost advantage over time, even if such changes tend to happen slowly.
Why the category matters
The broader lesson for investors is that unglamorous, mission-critical software categories — compliance, logistics, back-office workflow — often produce more durable economics than higher-growth, higher-visibility software niches, precisely because they are unglamorous. Competitors are less likely to pour venture capital into displacing a category that does not generate exciting headlines, and customers in these categories prioritize reliability over innovation, reinforcing incumbency. That dynamic does not make the shares immune to multiple compression, but it does mean the underlying franchise tends to be more resilient through a downturn than businesses selling discretionary software tools.
What to watch
Track organic revenue growth separately from acquisition-driven growth in quarterly disclosures, along with the split between recurring/subscription revenue and transaction-based revenue. Watch free cash flow conversion and the pace and size of tuck-in acquisitions relative to the balance sheet, as well as management commentary on integration progress for recently acquired businesses. Monitor global trade volume indicators and any customs or trade-policy developments that could affect cross-border shipping activity, and keep an eye on the multiple the market assigns relative to history as a gauge of how much execution risk is priced in.
Weiterlesen
Also in English: Descartes Systems and the Case for Unglamorous Software
 TechnologyDer Verteidigungsauftrag von Volatus Aerospace verpflichtet Kanada zu 100 Drohnen, nicht zu 5,000Volatus Aerospace Inc. meldete am 10. September 2026 einen fünfjährigen kanadischen Verteidigungsauftrag über taktische ISR-Drohnen mit einem Volumen von bis zu 5,000 Systemen. Fest vereinbart sind 100 Systeme. Die übrigen 4,900 sind Optionen, die allein nach Ermessen Kanadas ausgeübt werden, und das Unternehmen stellt ausdrücklich klar, dass es sich dabei weder um Käufe noch um Auftragsbestand oder Umsatz handelt. Bei einem genannten Höchstpreis von C$5,000 je System beträgt die Obergrenze insgesamt C$25 Millionen über fünf Jahre.Priya Sandhu · 14. September 2026 · 8 min
 TechnologyRekordvolumen bei LNG und 30 Prozent weniger Kontrakte insgesamt: Abaxx verlor 17.1 Prozent an der eigenen MeldungAbaxx Technologies schloss am 9. September 2026 bei C$18.04, ein Minus von 17.1 Prozent bei rund dem 1.2-Fachen des Dreißigtagedurchschnitts, an dem Tag, an dem das Unternehmen eine Mitteilung mit Rekordvolumen bei LNG-Futures im August veröffentlichte. Im Text derselben Mitteilung stand ein Gesamtvolumen von 377,949 Kontrakten gegenüber dem Julirekord von 543,100. Die Quartalszahlen vom 17. August zeigen, warum der Unterschied zählt: Transaktions- und Clearinggebühren von C$4,496,409 im zweiten Quartal gegenüber Liquiditätsgutschriften von C$4,494,753.Priya Sandhu · 10. September 2026 · 7 min
 EconomyVier in Kanada notierte Unternehmen meldeten diese Woche Staatsgeld, und keiner der Beträge war BargeldZwischen dem 15. und dem 18. September 2026 meldeten Conifex Timber, Global Atomic, First Phosphate und Bitterroot Resources jeweils, dass eine Regierung Geld hinter sie gestellt hat: bis zu C$30 Millionen, US$414.2 Millionen, US$212.5 Millionen und bis zu US$5.22 Millionen. Vier Meldungen, vier Instrumente, und keines davon ist eine Überweisung. Was ein Darlehensvertrag, eine bedingte Zusage, eine Exportkredit-Unterstützungserklärung und eine Kostenteilungszusage jeweils verpflichten, und was zutreffen muss, bevor das Geld ankommt.Marc Belzile · 19. September 2026 · 10 min
Dieser Geschichte folgen
DSG folgen – der nächste Maple-Beitrag zu diesem Unternehmen, dazu der Maple Morning Debrief vor Handelsbeginn.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. Lesen Sie den finanziellen Haftungsausschluss.
Quellen und Verweise (2)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Priya Sandhu (3. Juni 2026). Descartes Systems and the Case for Unglamorous Software. The Maple Markets. https://themaplemarkets.ca/de/newsroom/descartes-systems-and-the-case-for-unglamorous-softwarehttps://themaplemarkets.ca/de/newsroom/descartes-systems-and-the-case-for-unglamorous-software