
Lundin Gold's Fruta del Norte and the Single-Asset Discount
Lundin Gold trades at a discount to diversified producers despite owning one of the highest-grade gold mines built this century. This piece unpacks why single-asset concentration and Ecuadorian country risk drive that gap, and what capital allocation choices could eventually close it.
By Daniel Okoye3 min readTranslation: human
Cost position
Lowest quartile
Grade driven
Discount reason
Single asset
Concentration risk
Re-rating path
Mine life or M&A
Both carry risk
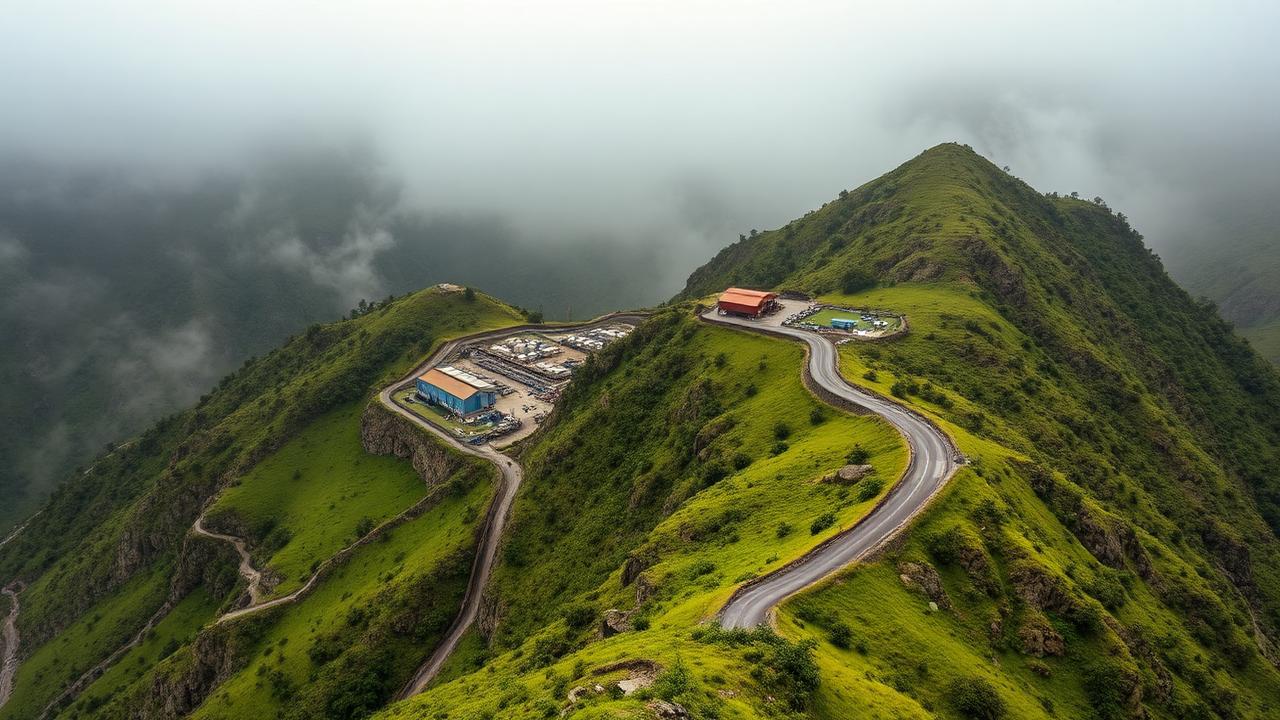
Fruta del Norte is among the higher-grade gold mines built this century, and Lundin Gold's valuation has consistently sat below diversified producers with less attractive assets. That gap is not a market oversight. It is the price the market extracts for owning one mine in one country, and understanding why that discount persists, and what could close it, matters more to an investor than admiring the ore grade itself.
The asset quality
High grade translates into all-in sustaining costs that sit in the lowest quartile of the global cost curve. At current gold prices that produces free cash flow generation disproportionate to the company's market capitalisation. A low-cost position also means the mine remains profitable through a much wider range of gold prices than higher-cost peers, which reduces downside risk in a way that headline valuation multiples do not always capture. Investors comparing Lundin Gold to diversified miners on a price-to-cash-flow basis are often comparing a lower-risk cash flow stream to a higher-risk one, without adjusting the multiple accordingly.
Why the discount exists
A single operating asset means a single point of failure. A geotechnical event, a mill outage, or a change in Ecuadorian fiscal or permitting policy affects one hundred per cent of revenue. Diversified producers absorb such events; single-asset companies do not. This is the structural reason single-asset miners trade at a discount to multi-asset peers across the sector, not something specific to Lundin Gold's execution record. The market is pricing tail risk that has not materialised, and it will keep doing so for as long as the company remains a one-mine story, regardless of how well that mine performs quarter after quarter.
Country risk as a distinct variable
Beyond operational concentration sits jurisdictional concentration. Ecuador is a newer mining jurisdiction relative to Canada or Australia, with a shorter track record of fiscal and regulatory stability through a full commodity cycle. Royalty terms, windfall taxes and permitting rules can shift with changes in government, and a single-asset company has no ability to reallocate capital to a friendlier jurisdiction if terms deteriorate. This is a different risk from the operational risk above: it is policy risk layered on top of geological and mechanical risk, and it compounds the single-asset discount rather than simply adding to it.
The path to re-rating
Either exploration success that extends mine life materially, or acquisition of a second asset. Extending mine life through the drill bit is the lower-risk route because it adds value to an asset the market already understands and has already underwritten operationally. It does not, however, solve the concentration problem; a longer-lived single mine is still a single mine. Acquisition of a second asset would directly address diversification, but it carries its own risk: single-asset producers buying diversification at cycle-high prices have a poor historical record. Gold miners in particular have a history of overpaying for growth assets when their own cash flow and share price are elevated, precisely the moment management teams feel most emboldened to deploy capital. A disciplined, counter-cyclical acquisition would be viewed very differently by the market than a rushed one funded by a strong balance sheet during a gold price spike.
Capital allocation as the swing factor
With free cash flow generation strong relative to market capitalisation, the company faces a familiar allocation choice: return capital directly to shareholders, retire debt, fund exploration, or pursue the acquisition discussed above. Each choice sends a different signal about management's own view of the discount. Heavy buybacks or dividends effectively concede that a second asset is not imminent and that the best use of cash is compensating shareholders for the single-asset risk they are bearing. A visible war chest building toward acquisition signals the opposite. Neither is inherently wrong, but the market will read the capital allocation pattern over several quarters as a proxy for management's own assessment of when, or whether, the discount is fixable.
What to watch
Track exploration results and any resource or reserve updates that extend stated mine life, since these directly address the durability half of the discount. Watch royalty, tax and permitting developments in Ecuador, including any legislative changes affecting mining, as these move the country-risk half. Monitor free cash flow trends and how management deploys them, particularly any signal of acquisition intent versus continued capital return. Finally, watch for operational disclosures around mill throughput, grade reconciliation and any geotechnical issues at Fruta del Norte, since a clean operating record over successive years is the only way the market gradually reduces the discount attached to single-asset concentration.
Weiterlesen
Also in English: Lundin Gold's Fruta del Norte and the Single-Asset Discount
 Mining and ResourcesFür Homeland Nickel läuft die Frist der Forstbehörde, doch die Bohrgenehmigung steht noch ausHomeland Nickel Inc. (TSXV: SHL) teilte am 17. September 2026 mit, der United States Forest Service habe seinen Betriebsplan für ein Sonic-Bohrprogramm in Red Flat, Oregon, angenommen, und die Umwelt- und Kulturgüterprüfung sei weit fortgeschritten, einschließlich abgeschlossener Feldarbeiten. Das Unternehmen hofft, im Oktober zu bohren. Dieselbe Mitteilung wurde am selben Tag erneut versandt, weil ihre Offenlegung zur bezahlten Bewerbung ein Videointerview mit dem Vorstandschef eines anderen Unternehmens beschrieb.Daniel Okoye · 18. September 2026 · 8 min
 Mining and ResourcesAya Gold and Silver hat in Zgounder 3.501 g/t Silber erbohrt und daraus noch nichts verkauftAya Gold & Silver Inc. (TSX: AYA) meldete am 16. September 2026 hochgradige Silberabschnitte nahe der Grube von Zgounder und in der Tiefe, acht Tage nachdem das Unternehmen den Papierwert seines Projekts Boumadine verdoppelt hatte, und fünfzehn Tage nach der Vereinbarung über den Kauf eines Kupfer-Silber-Konzessionspakets. Die Aktie schloss am 17. September bei C$40,24. Das Unternehmen hält US$182,8 Millionen an Barmitteln, und rund 80 Prozent des Metalls in der Boumadine-Studie liegen in der spekulativsten Ressourcenkategorie, die es gibt.Élise Galarneau · 18. September 2026 · 8 min
 Mining and ResourcesFirst Lithium Minerals eröffnet in vier Monaten die dritte Finanzierung, zu einem Preis über dem eigenen SchlusskursFirst Lithium Minerals Corp. (CSE: FLM, FSE: X28) hat am 16. September 2026 eine neue Privatplatzierung nach der Listed-Issuer-Financing-Ausnahme begonnen, die dritte seit Mai. Vollständig gezeichnet brächte sie rund C$5,0 Millionen und 44,6 Millionen neue Aktien gegenüber 112,2 Millionen bereits ausstehenden. Das eigene Angebotsdokument vom Juli bezifferte das Betriebskapital auf rund C$100.000 und trug einen Going-Concern-Hinweis. Die Frankfurter Notierung existiert und machte am 17. September keinen Umsatz.Priya Sandhu · 18. September 2026 · 8 min
Dieser Geschichte folgen
LUG folgen – der nächste Maple-Beitrag zu diesem Unternehmen, dazu der Maple Morning Debrief vor Handelsbeginn.
Folgen und fragen
Mehr von unserer Berichterstattung zu den kanadischen Märkten in Google Top Stories.
Offenlegung
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. Lesen Sie den finanziellen Haftungsausschluss.
Quellen und Verweise (2)
Diese Analyse zitieren
Bitte The Maple Markets nennen und auf die Originalseite verlinken.
Daniel Okoye (24. Juni 2026). Lundin Gold's Fruta del Norte and the Single-Asset Discount. The Maple Markets. https://themaplemarkets.ca/de/newsroom/lundin-gold-s-fruta-del-norte-and-the-single-asset-discounthttps://themaplemarkets.ca/de/newsroom/lundin-gold-s-fruta-del-norte-and-the-single-asset-discount