93% of Aya Gold and Silver's Revenue Came From Silver
The company's name says gold and silver, its mine sells almost nothing but silver, and the deposit it is spending 14 drill rigs on would change that mix if it is ever built.
Aya Gold & Silver reported US$96.8 million of revenue for the June 2026 quarter, of which US$90.3 million came from silver and US$6.5 million from pyrite. No gold revenue line appears. The pure-play silver description that circulates among shareholders is supported by the current filings, and the Boumadine deposit Aya is drilling with 14 rigs is polymetallic enough to end it.
By Daniel Okoye7 min read
Q2-2026 revenue mix
US$90.3 million silver and US$6.5 million pyrite, of US$96.8 million total
93.3 per cent from silver, three months ended 30 June 2026 (Aya Q2-2026 results release, 13 August 2026)
Silver production and realised price
1.59 million ounces consolidated, at US$68.29 per ounce realised
against 1,400 ounces of gold from the Boumadine pyrite reclaim, June 2026 quarter (same release)
Cash position
US$182.8 million, plus US$16 million restricted
at 30 June 2026; the EBRD facility of US$15 million was repaid in the quarter (same release)
Boumadine intercept composition
593 g/t silver equivalent over 15.2 m, being 1.05 g/t gold, 319 g/t silver, 5.3% zinc, 3.5% lead
hole BOU-DD26-883, true width undetermined, values uncut (release of 22 September 2026)
Share price and market value
C$38.69, up 2.76%, about C$5.57 billion
29 September 2026, on 0.55 times thirty-day average volume (QuoteMedia, 15-minute delayed; secondary market data, not verified against SEDAR+)
Aya Gold & Silver Inc. sells almost nothing but silver. For the three months ended 30 June 2026, one metal produced 93.3 per cent of the company's revenue.
The breakdown is in the quarterly results. Of US$96.8 million of revenue, silver accounted for US$90.3 million and pyrite, an iron sulphide sold as a by-product, accounted for US$6.5 million. There is no gold revenue line at a company whose name contains two metals.
The description that circulates among Aya's shareholders, that this is the closest thing on the Toronto exchange to pure silver exposure, is not shareholder enthusiasm running ahead of the filings. For the June quarter it is what the filings say. The more useful question is whether it stays true, and the company's own growth plan is the reason to ask.
The mine that makes the claim true
Zgounder, in Morocco's Anti-Atlas, is described by Aya as a silver-only mine, and the production figures bear the description out. In the June 2026 quarter Zgounder produced 1.49 million ounces of silver. Consolidated silver production was 1.59 million ounces, with the balance coming from a pyrite reclaim operation at Boumadine. Gold production for the quarter was 1,400 ounces, reported as 0.0014 million ounces and drawn entirely from that same reclaim operation.
Set those against each other and the scale gap is the point. At the realised silver price Aya reported for the quarter, US$68.29 an ounce, 1.32 million ounces of silver sold produced the US$90.3 million silver line. Fourteen hundred ounces of gold, at any gold price anyone has seen, is a rounding item. It does not reach the revenue statement as its own line because there is not enough of it to warrant one.
This is a genuinely unusual position for a precious-metals producer. Most companies that market themselves on silver are polymetallic mines where silver is one of four payable metals and often not the largest. A producer whose revenue is over ninety per cent silver, from a mine the company itself calls silver-only, is rare, and the shareholders who describe Aya that way are describing the accounts accurately.
The quarter was also a good one by the ordinary measures. Aya reported net income of US$35.0 million, basic earnings of US$0.24 a share, cash costs of US$17.69 per silver ounce sold at Zgounder against that US$68.29 realised price, and US$182.8 million of cash and cash equivalents at 30 June 2026 with a further US$16 million restricted. A US$15 million facility from the European Bank for Reconstruction and Development was repaid during the quarter. A company with a wide margin, real cash and a repaid loan is in a materially stronger position than one without, and the pure-play framing is being applied to a business that is currently working.
Why the next two years put that mix at risk
Boumadine is the reason Aya is worth more than Zgounder's cash flow, and Boumadine is not a silver deposit.
The drill results Aya reported on 22 September 2026 make this plain once the units are unpacked. Three of the headline intercepts:
- Hole BOU-DD26-883 returned 593 grams per tonne silver equivalent over 15.2 metres. The components were 1.05 g/t gold, 319 g/t silver, 5.3 per cent zinc and 3.5 per cent lead.
- Hole BOU-DD26-848 returned 392 g/t silver equivalent over 24.3 metres, from 0.61 g/t gold, 239 g/t silver, 2.6 per cent zinc and 1.9 per cent lead.
- Hole BOU-DD26-834 returned 696 g/t silver equivalent over 5.7 metres, from 2.70 g/t gold, 342 g/t silver, 3.8 per cent zinc and 1.3 per cent lead.
Silver equivalent is a convenience, not a measurement. It converts every metal in an intercept into the amount of silver that would be worth the same at an assumed set of prices, so that one number can stand for four. It is useful for comparing holes and misleading for anything else, because it hides what is actually in the rock.
What is actually in the rock at Boumadine, on those three holes, is silver plus meaningful gold plus base metals at grades that would be the whole story at a zinc mine. Zinc at 5.3 per cent is not a trace. A deposit with that composition, if it is built, sells zinc concentrate and lead concentrate and pays for gold, and its revenue does not look like Zgounder's.
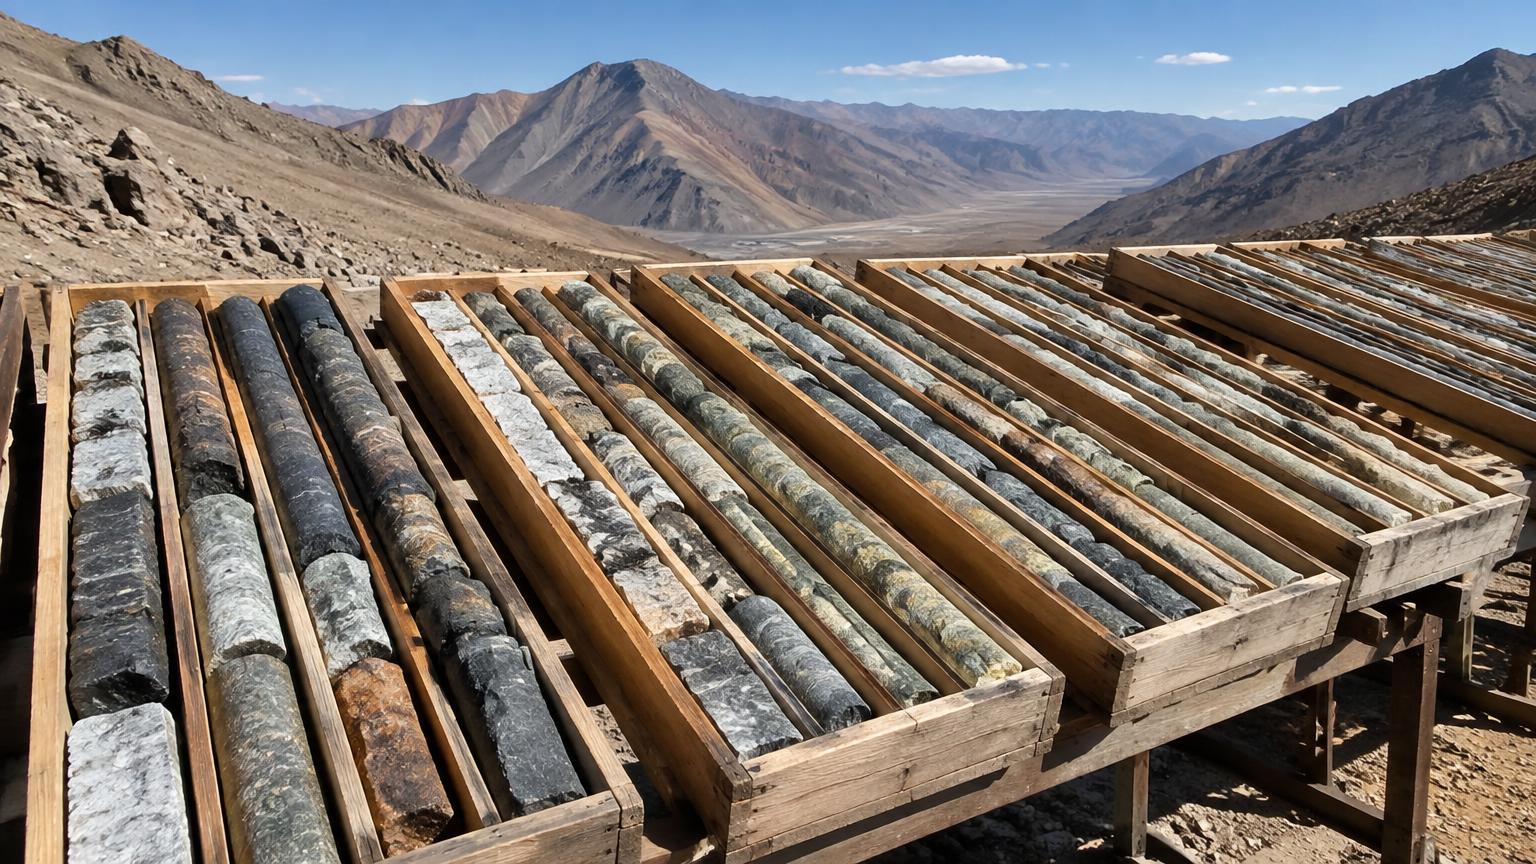
Aya has 14 drills turning at Boumadine and expects an updated feasibility study next year. The company reports true width remains undetermined at this stage and that all values are uncut, which are the standard and correct qualifications for exploration intercepts. Samples were assayed by the African Laboratory for Mining and Environment in Marrakech, with standards and blanks inserted every twenty samples, and the technical information was approved by David Lalonde, P.Geo., executive vice-president exploration.
A drill intercept is not a resource and a resource is not a mine. But the direction of travel is not ambiguous. The asset Aya is spending its exploration budget on is polymetallic, and the mix that makes the pure-play description true today is a description of the mine that exists, not of the company being built.
The claim that could not be checked
One item circulating alongside the pure-play framing does not survive contact with a source. An interview is said to have contained the claim that no investment vehicle offers one hundred per cent silver exposure. No named interview, publication or date was available to check that against, and it is not a statement Aya has made in any release reviewed here. It is not evidence and it does not belong in an assessment of the company. It is also, as a factual proposition about the whole market for silver exposure, the kind of claim that would need a great deal more support than a remark in conversation.
The comparison with First Majestic Silver that accompanies it is a different matter and can be made properly, but only on disclosed figures from both companies, which is a piece of arithmetic rather than an assertion. It is not done here, and it should not be asserted without being done.
Retail discussion of Aya over the past day has been thin, with two posts against roughly fifty across the week, and nobody arguing against the company. A quiet board on a name with no fresh release is an absence of information, not a signal.
What is pending, and what is not
Aya's most recent release was the 22 September Boumadine drill results. Nothing has been announced since. The shares closed at C$38.69 on 29 September 2026, up 2.76 per cent, on 0.55 times their thirty-day average volume, for a market value of about C$5.57 billion (QuoteMedia, 15-minute delayed; secondary market data, not verified against SEDAR+). That share count and market value are exchange data; the cash and revenue figures above come from the company's Q2-2026 results release of 13 August 2026.
The updated Boumadine feasibility study expected in 2027 is the document that settles the mix question, because a feasibility study has to state a metal-by-metal revenue split, recovery assumptions and concentrate marketing terms. Until it exists, the polymetallic character of Boumadine is visible in drill holes and absent from the income statement.
So both things are true at once, and neither cancels the other. Aya today is a silver producer with a wide margin, a strong balance sheet and a revenue mix that is 93 per cent one metal. Aya in 2029 or 2030, if Boumadine is built as the drilling suggests, is a company selling four metals from two mines in Morocco.
The name on the ticker has said gold and silver the whole time. It is the accounts, not the name, that made the pure-play description accurate, and it is a feasibility study rather than a headline that will say whether it stays that way.
Transparency note
Transparency note. This is an independent due-diligence analysis and editorial opinion piece produced by The Maple Markets editorial desk. It is not sponsored, promoted or commissioned, and no compensation of any kind has been received from Aya Gold & Silver Inc. (TSX: AYA), First Majestic Silver Corp. or any party acting on their behalf. The analysis is based on public disclosure available as of the publish date; every figure is attributed to its primary source. The Maple Markets and its authors may hold positions in securities mentioned; nothing here is a recommendation to buy, sell or hold any security, and readers should not treat it as investment advice. Past disclosure does not guarantee future results. Policies: Editorial Standards · Financial Disclaimer.
Read next
Auch auf Deutsch: 93 % der Erlöse von Aya Gold & Silver entfielen im Juniquartal auf Silber
 Mining and ResourcesAya Gold and Silver Has Drilled 3,501 g/t Silver at Zgounder and Sold Nothing From It YetAya Gold & Silver Inc. (TSX: AYA) reported high-grade silver intercepts near the Zgounder pit and at depth on September 16, 2026, eight days after doubling the paper value of its Boumadine project and fifteen days after agreeing to buy a copper-silver land package. The shares closed at C$40.24 on 17 September. The company holds US$182.8 million of cash, and about 80 per cent of the metal in the Boumadine study is in the most speculative resource category there is.Élise Galarneau · September 18, 2026 · 8 min
 Mining and ResourcesAya Gold and Silver Built the Mill It Promised, and That Is Why Its Second Project Gets a HearingAya Gold and Silver's mill at Zgounder ran at 3,889 tonnes a day in the second quarter of 2026, against 1,236 tonnes a day in the quarter it declared commercial production. The gap between those two numbers is a case study in how a junior producer earns credibility, and in what that credibility does and does not cover.Élise Galarneau · September 13, 2026 · 9 min
 Mining and ResourcesAya Gold and Silver Drills 593 g/t Silver Equivalent Over 15.2 Metres With 14 Rigs Turning at BoumadineAya Gold & Silver Inc. (TSX: AYA; NASDAQ: AYA) reported high-grade drill results from Boumadine in Morocco on September 22, 2026, including 593 g/t silver equivalent over 15.2 metres and 392 g/t over 24.3 metres. The company says the holes confirm strong high-grade continuity along the Main Trend. Behind the intercepts sits the larger number: 145,719 metres drilled at Boumadine this year, 38.6 per cent of a 360,000-metre infill programme, with 14 drills turning and an updated feasibility study expected next year. Shares closed at a record C$42.68, up 6.1 per cent.Élise Galarneau · September 23, 2026 · 8 min
Follow this story
Follow AYA.TO — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Opinion
This article expresses the author's personal views, is separate from news reporting and is not investment advice.
Disclosure
Transparency note. This is an independent due-diligence analysis and editorial opinion piece produced by The Maple Markets editorial desk. It is not sponsored, promoted or commissioned, and no compensation of any kind has been received from Aya Gold & Silver Inc. (TSX: AYA), First Majestic Silver Corp. or any party acting on their behalf. The analysis is based on public disclosure available as of the publish date; every figure is attributed to its primary source. The Maple Markets and its authors may hold positions in securities mentioned; nothing here is a recommendation to buy, sell or hold any security, and readers should not treat it as investment advice. Past disclosure does not guarantee future results. Policies: Editorial Standards · Financial Disclaimer. See the Financial Disclaimer.
Sources and references (5)
- Aya Gold & Silver Reports Q2-2026 Results and Delivers Record Operational Performance, 13 August 2026
- Aya Gold & Silver Reports High-Grade Drill Exploration Results at Boumadine, GlobeNewswire, 22 September 2026
- Aya Gold & Silver Reports Record Q2-2026 Silver Production, company release, 8 July 2026
- Aya Gold & Silver news releases archive
- Aya Gold and Silver Drills 593 g/t Silver Equivalent Over 15.2 Metres With 14 Rigs Turning at Boumadine, The Maple Markets, 22 September 2026
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Daniel Okoye (September 30, 2026). 93% of Aya Gold and Silver's Revenue Came From Silver. The Maple Markets. https://themaplemarkets.ca/en/newsroom/aya-gold-silver-pure-play-is-a-revenue-mix-claim-aya-gold-and-silverhttps://themaplemarkets.ca/en/newsroom/aya-gold-silver-pure-play-is-a-revenue-mix-claim-aya-gold-and-silver