
Canada's Housing Starts Data Is Telling Two Different Stories
A steady national housing-starts headline is masking a sharp split between resilient multi-unit construction and falling single-family building. This piece explains the financing mechanics behind the divergence and why materials investors should track the mix, not the total.
By Marc Belzile3 min readTranslation: human
Multi-unit starts
Holding
Rental and condo
Single-family starts
Falling
Rate sensitive
Weakest regions
ON and BC
Land and financing costs
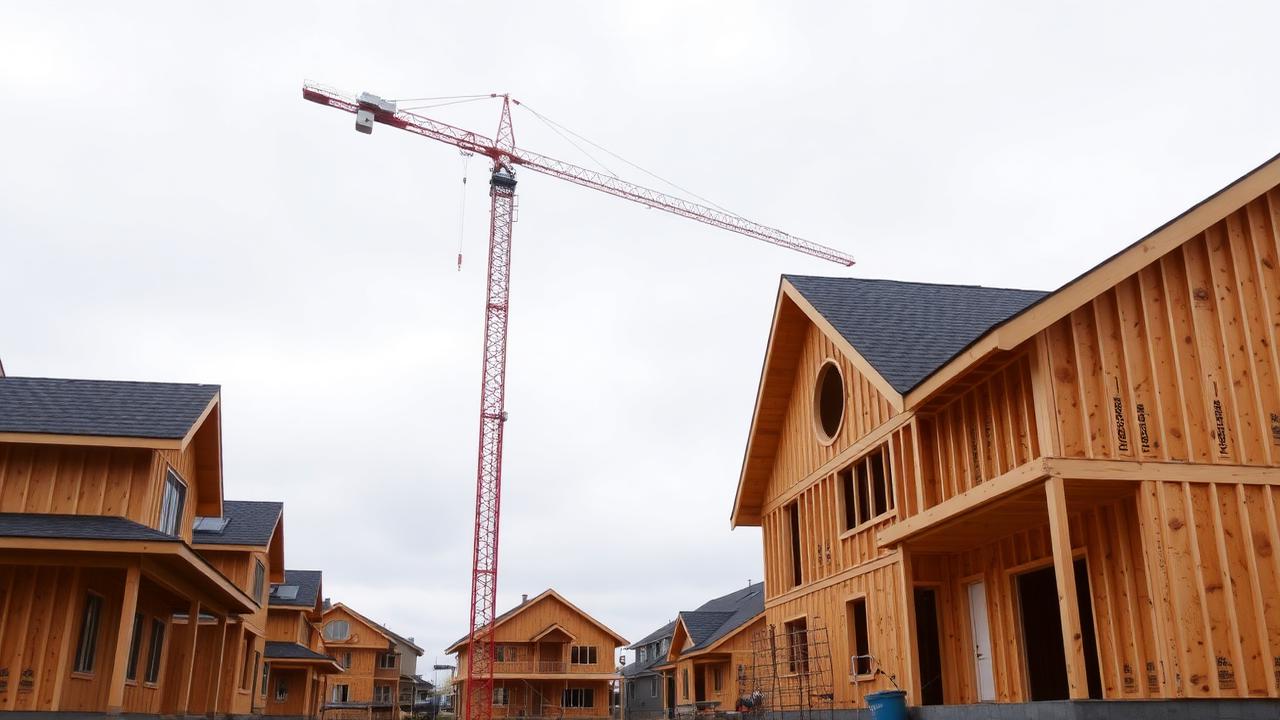
The national housing-starts figure moved only modestly in the latest release, and that modest headline obscured a sharp divergence beneath it: purpose-built rental and condominium starts held up while single-family construction fell. Reading only the top-line number would leave an investor with a materially incomplete, and in some respects misleading, picture of what is actually happening in Canadian residential construction.
Why the split is happening
Financing costs bite hardest on speculative single-family builders who work with short project horizons and rely on presale or spot-market demand to justify breaking ground. When financing conditions tighten, these builders are the first to pull back, because their projects lack the long-term financing arrangements and pre-committed demand that larger multi-unit developments typically have in place. Multi-unit projects, often supported by federal financing programs and pre-sold or pre-leased before construction begins, carry fundamentally different economics. A rental building financed through a program with favourable long-term terms and backed by a projected rent roll is insulated from a single quarter's interest rate environment in a way that a single-family spec builder simply is not. That structural difference is the mechanism behind the divergence, not a temporary anomaly that will resolve itself.
Regional divergence
Ontario and British Columbia account for most of the single-family weakness in the national data, which is consistent with those two markets having the highest land and construction costs in the country and therefore the thinnest margins for speculative building when financing costs rise. The Prairies have been comparatively resilient, reflecting both lower land costs, which preserve builder margins at a wider range of financing conditions, and population inflows that have not yet fully translated into supply. That gap between population growth and housing supply in Prairie markets is itself worth watching, because a persistent gap tends to eventually show up in either accelerating construction activity or worsening affordability metrics, and which of those two outcomes materialises has different implications for regional homebuilders and materials suppliers.
Reading the mix, not just the level
Investors and policymakers alike tend to anchor on the seasonally adjusted annualized rate of total starts because it is the headline figure reported, but the composition of that total matters as much as the level. A national total held up by multi-unit starts concentrated in a few urban markets is a different signal for the broader economy than the same total driven by a broad-based increase across housing types and regions. Multi-unit and single-family construction also draw on different segments of the labour force and different materials inputs, so a shift in mix has real implications beyond the headline number, feeding through to employment patterns in the construction trades and to demand for specific categories of building materials.
What it means for markets
Building-materials and forestry names, particularly those exposed to lumber and other wood products used predominantly in single-family and low-rise wood-frame construction, track single-family volumes far more closely than they track headline starts. An investor extrapolating strength in the national starts number to strength in lumber demand will be reading the wrong series, because the segment of construction actually driving that demand is the one that is currently declining. Conversely, companies exposed to concrete, structural steel and the trades used disproportionately in taller multi-unit construction are better aligned with the segment of the market that is currently holding up.
The policy dimension
Federal financing programs supporting purpose-built rental construction are a deliberate policy lever aimed at addressing a rental supply shortage, and their continued availability and terms are a direct input into how much of the current multi-unit resilience is structural versus temporarily subsidized. Any material change to the terms, availability or eligibility criteria of those programs would be expected to show up in the multi-unit starts data with a lag, given typical project financing and approval timelines, making the durability of current program terms a relevant factor for anyone forecasting multi-unit starts several quarters forward.
What to watch
Track the seasonally adjusted starts data broken out by single-family versus multi-unit and by region, rather than the blended national headline; the terms and uptake of federal rental construction financing programs; regional population growth relative to housing completions in fast-growing Prairie and Western markets; and lumber and building-materials shipment volumes as a cross-check against the single-family starts trend specifically.
Read next
 Real EstateCanada's Mortgage Renewal Shock Is Becoming More SelectiveAbout 12% of outstanding mortgages still face the pandemic-vintage reset, with an average payment increase near 15%. National arrears remain low. The risk is concentrating rather than broadening.Hannah Kuan · September 3, 2026 · 7 min
 Real EstateThe Mortgage Renewal Wall: Doing the Payment Shock MathCanadian mortgages renew every few years, not every thirty. That structural difference concentrates rate risk into renewal windows, and the arithmetic is more specific than the headlines suggest.Priya Sandhu · August 31, 2026 · 8 min
 Real EstateCanadian REITs: AFFO Payout Ratios and the Refinancing ArithmeticA REIT distribution is safe until the debt behind it reprices. Here is how to read the payout ratio, the maturity ladder and the interest coverage covenant together rather than separately.Priya Sandhu · August 19, 2026 · 8 min
Get the Maple Morning Debrief
Yesterday's close, overnight, and what to watch before the open — in your inbox by 6 a.m. ET. Free, and one click to unsubscribe.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Disclosure
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. See the Financial Disclaimer.
Sources and references (3)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Marc Belzile (April 29, 2026). Canada's Housing Starts Data Is Telling Two Different Stories. The Maple Markets. https://themaplemarkets.ca/en/newsroom/canada-s-housing-starts-data-is-telling-two-different-storieshttps://themaplemarkets.ca/en/newsroom/canada-s-housing-starts-data-is-telling-two-different-stories