
Methanex and the Cyclicality Investors Keep Underestimating
Methanex's earnings swing harder than most industrial companies because of high operating leverage and volatile natural gas feedstock costs. This piece explains the mechanics behind that cyclicality and why marine-fuel demand, while structural, is not yet large enough to smooth it out.
By Hannah Kuan3 min readTranslation: human
Cost structure
High fixed
Amplifies price moves
Feedstock
Natural gas
Availability risk
Growth application
Marine fuel
Emissions driven
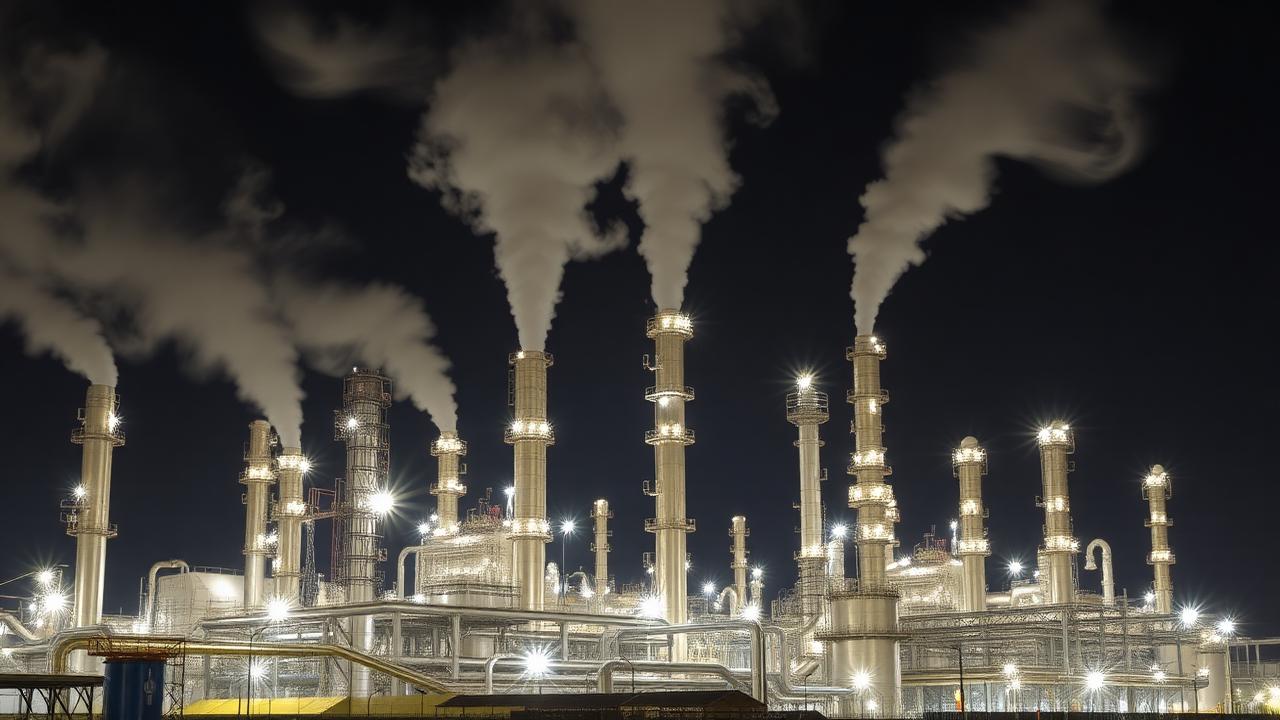
Methanex produces a single commodity chemical, prices it against a global benchmark, and buys natural gas as its principal feedstock. Each of those facts amplifies the earnings cycle. Investors who model Methanex like a diversified industrial company, smoothing revenue and margin assumptions across years, consistently misjudge both the upside and the downside, because the business is built to swing.
The operating leverage
Fixed production costs are high relative to variable costs. A modest change in the realised methanol price therefore produces a much larger change in operating income. In strong markets this is spectacular; in weak markets it is brutal. This operating leverage is a direct consequence of the plant economics: methanol production is capital-intensive with large, largely fixed conversion costs, so once a plant is running, most of the incremental revenue from a higher price drops straight to operating income. The reverse is equally true on the way down. This is why methanol producers as a group trade at lower earnings multiples than more diversified chemical companies during upcycles; the market is discounting the certainty that today's income statement will not persist.
Feedstock is the other lever
Natural gas supply agreements in several producing jurisdictions are priced at a discount to global markets, sometimes with variable components. Gas availability, particularly in jurisdictions with domestic allocation policies, has interrupted production repeatedly. This creates a second, partially independent source of cyclicality layered on top of the methanol price cycle. A producer can face weak product prices and simultaneously face a feedstock disruption, or the two can move in offsetting directions. The variable-component contracts also mean that reported cost of goods sold is not a fixed input an investor can extrapolate; it moves with local gas market conditions that are themselves subject to domestic policy decisions unrelated to the global methanol market.
Geographic diversification of production
Operating plants across multiple countries and feedstock regimes is the company's main structural response to both sources of cyclicality described above. Diversifying production geography does not eliminate the exposure to the global benchmark methanol price, since that price is set globally regardless of where a given plant sits, but it does reduce the odds that a single jurisdiction's gas allocation policy or a single plant's operational issue removes all supply at once. It is a mitigant to feedstock and operational risk, not to price risk, and the distinction matters when assessing what geographic footprint actually protects against.
Demand drivers
Methanol goes into formaldehyde, olefins, fuel blending and marine fuel. The formaldehyde and broader industrial-chemical applications track general industrial production and construction activity, which is itself cyclical and correlated with the same macro conditions that drive methanol pricing. The olefins application, where methanol is converted into base petrochemical building blocks in certain regions, links methanol demand to the economics of alternative feedstocks for the same downstream products, adding another layer of price sensitivity. The marine-fuel application is the genuine structural growth story, driven by emissions regulation, and it is not yet large enough to offset the industrial cycle. Its trajectory depends on the pace of vessel ordering and regulatory enforcement rather than on near-term economic conditions, which makes it a slower-moving but more durable demand driver than the industrial end uses.
Reading the cycle correctly
Because both the revenue line and the cost line are volatile and not always correlated, quarter-to-quarter earnings for a company like this are a poor guide to underlying value. The more useful exercise is tracking the position in the methanol price cycle relative to the industry's marginal cost of production, since high-cost capacity idling or restarting is what ultimately sets a floor and ceiling on price over a full cycle. An investor underwriting the stock through a single strong or weak quarter, rather than through where the industry sits in its capacity and pricing cycle, is the one most likely to misprice the shares.
What to watch
Track the realised methanol price against regional benchmarks and how that compares with the industry's marginal cost curve. Watch feedstock gas cost disclosures by region, especially any jurisdiction with domestic allocation rules, for signs of cost inflation or supply interruption. Monitor plant utilisation and any unplanned outages, since fixed costs mean idle capacity is disproportionately damaging to margins. Follow marine-fuel adoption data and regulatory milestones as the clearest signal of the structural, non-cyclical portion of demand growth.
Read next
 Businessgoeasy's Repair Is Working, but the Earnings Model Has Not Recoveredgoeasy's charge-offs and leverage improved sequentially in the second quarter. Originations fell 70% year over year and adjusted diluted EPS fell to $1.02 from $4.40. Repair is not reacceleration.Hannah Kuan · September 1, 2026 · 8 min
 BusinessCanadian Grocery Margins: Pricing Power Under Political ScrutinyCanadian grocers earn thin margins on food and better margins on everything else in the store. The public debate conflates the two, and so do a lot of investors.Hannah Kuan · August 31, 2026 · 7 min
 BusinessNI 43-101 Versus the Press Release: Detecting Selective DisclosureCanada's mining disclosure standard is among the strictest in the world. It constrains the technical report — and press releases are where the pressure escapes.Daniel Okoye · August 29, 2026 · 8 min
Follow this story
Follow MX — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Disclosure
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. See the Financial Disclaimer.
Sources and references (2)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Hannah Kuan (July 13, 2026). Methanex and the Cyclicality Investors Keep Underestimating. The Maple Markets. https://themaplemarkets.ca/en/newsroom/methanex-and-the-cyclicality-investors-keep-underestimatinghttps://themaplemarkets.ca/en/newsroom/methanex-and-the-cyclicality-investors-keep-underestimating