
Canada's Trade Balance and the Concentration Problem
Canada's exports remain unusually concentrated in a single destination market, a structural feature that two decades of diversification efforts have barely moved. This piece explains why that concentration is a direct earnings risk for TSX-listed exporters, not just a macro footnote.
By Élise Galarneau3 min readTranslation: human
Cet article n'est offert qu'en anglais pour le moment.
Export destination
Predominantly US
Unusual concentration
Top categories
Energy, autos, forestry
Policy exposed
Diversification
Infrastructure limited
Multi-year
Canada's merchandise trade data continues to show an export base concentrated in one destination market to a degree unusual among developed economies. That concentration is not a new development, but it is one that periodically moves from background context to a first-order market variable whenever trade policy in the destination market shifts, and understanding the mechanism behind the concentration is more useful to an investor than any single month's trade balance print.
The concentration
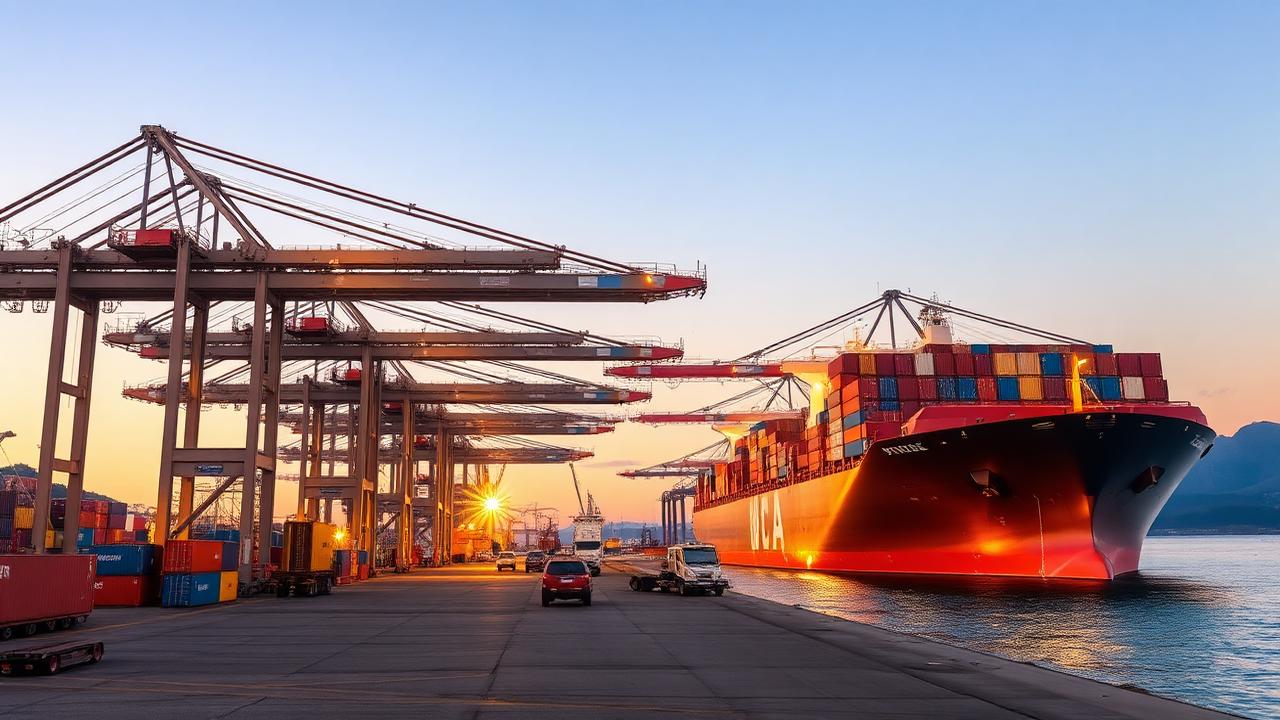
The overwhelming majority of Canadian merchandise exports go to the United States, a share that dwarfs the export concentration seen in most other advanced economies, which typically spread trade across a more diversified set of partners. Energy, motor vehicles and forest products dominate the export mix, three categories that are each, for different structural reasons, tightly integrated with US demand and, in the case of energy and autos, with US physical infrastructure and supply chains that took decades to build. Diversification initiatives launched over multiple governments and multiple trade agreements have shifted the numbers only marginally over two decades, which suggests the concentration reflects durable structural factors, principally proximity, integrated supply chains and existing pipeline and transportation infrastructure, rather than simply an absence of policy effort.
Why it is a market risk
Tariff proposals, content requirements and border measures originating in the United States affect a large share of Canadian corporate revenue directly, because so much of that revenue is generated by selling into that single market. This is not a background macro consideration that shows up eventually in aggregate GDP figures; it is a direct input into the earnings of specific TSX-listed companies in the energy, automotive and forestry sectors, and the transmission from a policy announcement to an earnings impact can be fast, sometimes faster than the market fully prices in the initial reaction. The autos sector is a particularly clear illustration, because vehicles and parts often cross the Canada-US border multiple times during assembly, meaning a tariff or content rule does not just affect final export sales but the entire integrated production process.
The energy dimension specifically
Energy exports carry an additional layer of concentration risk beyond the destination market itself, because a large share of Canadian oil exports move through pipeline infrastructure built specifically to serve US refining capacity, with limited alternative export routes to other markets. That infrastructure constraint means Canadian energy producers have historically had less ability than commodity producers in other countries to redirect exports toward alternative buyers in response to price or policy changes in the primary market, which is a structural feature of the sector distinct from, but related to, the broader trade concentration issue.
What would change it
Meaningful diversification of the Canadian export base requires export infrastructure oriented toward other markets, including port capacity capable of handling greater volumes, pipeline routing to tidewater that would allow energy exports to reach non-US buyers, and trade agreements with enforcement mechanisms robust enough to give exporters confidence to invest in new customer relationships and supply chains outside North America. Each of these requires long lead times and substantial capital investment, and each has, in various forms, been discussed as policy over the past two decades without producing a large shift in the underlying export concentration figures. That track record is itself informative: an investor should treat announcements of new diversification initiatives as multi-year propositions rather than developments that will show up quickly in trade balance data.
How markets have historically priced this risk
Because the underlying concentration has been stable for a long period, the market has tended to underprice the risk between episodes of active trade tension and to reprice it sharply once a specific policy proposal or measure is announced. That pattern of episodic repricing, rather than a steady, continuously priced-in risk premium, is a useful thing for an investor in trade-exposed sectors to recognize, because it means the relevant catalysts are political and policy announcements specifically, not gradual shifts in the underlying trade data itself.
What to watch
Track monthly merchandise trade balance data broken out by destination and by sector, particularly the energy, automotive and forest products categories; any US tariff, content-requirement or border-measure proposals and their specific sectoral scope; progress, or lack of it, on port and pipeline infrastructure projects aimed at export diversification; and the status of trade agreement negotiations or renewals affecting the terms of Canada-US trade specifically.
À lire ensuite
Auch auf Deutsch: Canada's Trade Balance and the Concentration Problem
 EconomyA Canadian Company Can Watch Its Shares Fall All Week and Owe the Market Nothing at AllCanadian issuers must announce a material change immediately and file the report within 10 days. They are not required to publish every material fact, and they are not required to explain a share price. That single distinction explains most of the weeks when a Canadian small cap moves and SEDAR+ stays empty. Here is what the rules actually oblige, what the exchanges do when the price moves first, which filings arrive from someone other than the company, and the calendar that governs a quiet month.Élise Galarneau · 19 septembre 2026 · 8 min
 EconomyFour Canadian-Listed Companies Announced Government Money This Week, and None of It Was CashBetween September 15 and September 18, 2026, Conifex Timber, Global Atomic, First Phosphate and Bitterroot Resources each announced that a government had put money behind them: up to C$30 million, US$414.2 million, US$212.5 million and up to US$5.22 million. Four announcements, four instruments, and not one of them is a transfer of cash. Here is what a loan agreement, a conditional approval, an export-credit letter of support and a cost-share award each oblige, and what has to be true before the money arrives.Marc Belzile · 19 septembre 2026 · 10 min
 EconomyFour Things a Canadian Miner Can Say About a Hole in the Ground, and What Each Is WorthA Canadian explorer with no laboratory numbers rose 93.8 per cent on September 9, 2026. A company that published laboratory numbers fell 35 per cent the next day. Canadian mining disclosure runs on four separate stages of proof, and most of the confusion in a drill-results week comes from treating them as one.Priya Sandhu · 13 septembre 2026 · 9 min
Recevoir le Maple Morning Debrief
La clôture de la veille, la nuit et ce qu'il faut surveiller avant l'ouverture — dans votre boîte de réception avant 6 h HE. Gratuit, désabonnement en un clic.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Divulgation
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed. See the Financial Disclaimer.
Sources et références (3)
Citer cette analyse
Please attribute The Maple Markets and link to the original page.
Élise Galarneau (June 29, 2026). Canada's Trade Balance and the Concentration Problem. The Maple Markets. https://themaplemarkets.ca/fr/newsroom/canada-s-trade-balance-and-the-concentration-problemhttps://themaplemarkets.ca/fr/newsroom/canada-s-trade-balance-and-the-concentration-problem