
Canada's Trade Balance and the Concentration Problem
Canada's exports remain unusually concentrated in a single destination market, a structural feature that two decades of diversification efforts have barely moved. This piece explains why that concentration is a direct earnings risk for TSX-listed exporters, not just a macro footnote.
By Élise Galarneau3 min readTranslation: human
Export destination
Predominantly US
Unusual concentration
Top categories
Energy, autos, forestry
Policy exposed
Diversification
Infrastructure limited
Multi-year
Canada's merchandise trade data continues to show an export base concentrated in one destination market to a degree unusual among developed economies. That concentration is not a new development, but it is one that periodically moves from background context to a first-order market variable whenever trade policy in the destination market shifts, and understanding the mechanism behind the concentration is more useful to an investor than any single month's trade balance print.
The concentration
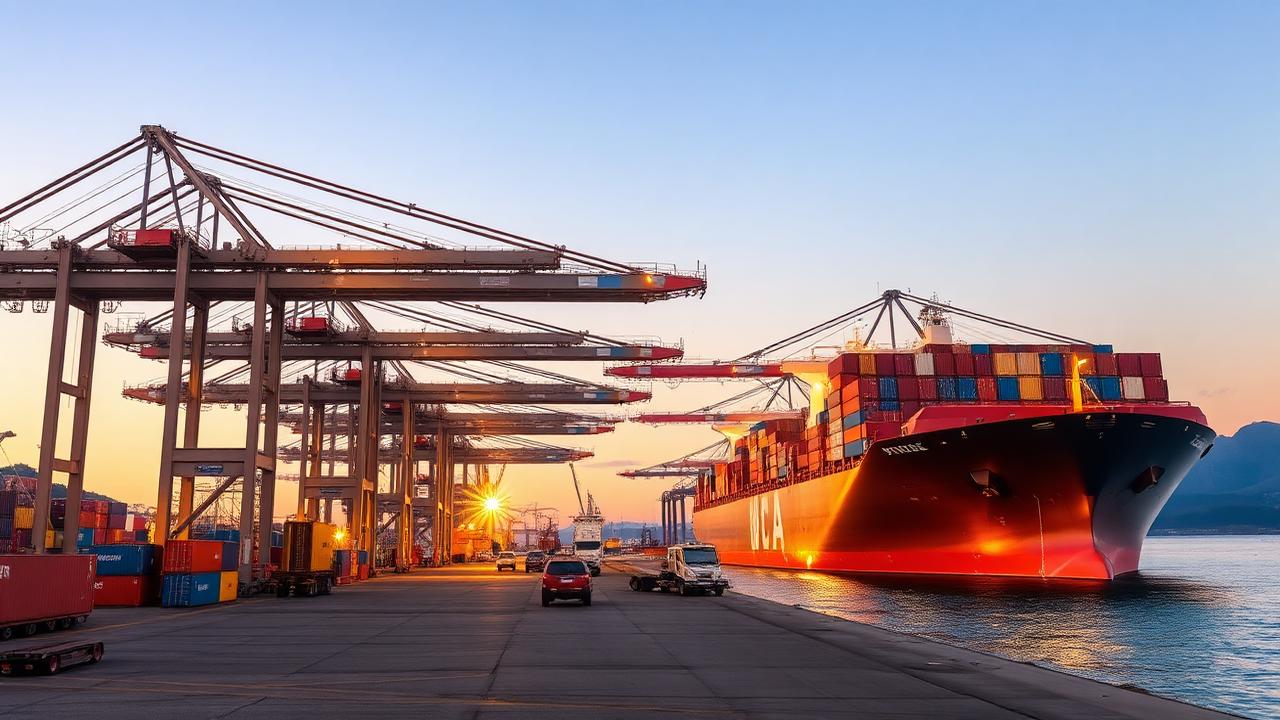
The overwhelming majority of Canadian merchandise exports go to the United States, a share that dwarfs the export concentration seen in most other advanced economies, which typically spread trade across a more diversified set of partners. Energy, motor vehicles and forest products dominate the export mix, three categories that are each, for different structural reasons, tightly integrated with US demand and, in the case of energy and autos, with US physical infrastructure and supply chains that took decades to build. Diversification initiatives launched over multiple governments and multiple trade agreements have shifted the numbers only marginally over two decades, which suggests the concentration reflects durable structural factors, principally proximity, integrated supply chains and existing pipeline and transportation infrastructure, rather than simply an absence of policy effort.
Why it is a market risk
Tariff proposals, content requirements and border measures originating in the United States affect a large share of Canadian corporate revenue directly, because so much of that revenue is generated by selling into that single market. This is not a background macro consideration that shows up eventually in aggregate GDP figures; it is a direct input into the earnings of specific TSX-listed companies in the energy, automotive and forestry sectors, and the transmission from a policy announcement to an earnings impact can be fast, sometimes faster than the market fully prices in the initial reaction. The autos sector is a particularly clear illustration, because vehicles and parts often cross the Canada-US border multiple times during assembly, meaning a tariff or content rule does not just affect final export sales but the entire integrated production process.
The energy dimension specifically
Energy exports carry an additional layer of concentration risk beyond the destination market itself, because a large share of Canadian oil exports move through pipeline infrastructure built specifically to serve US refining capacity, with limited alternative export routes to other markets. That infrastructure constraint means Canadian energy producers have historically had less ability than commodity producers in other countries to redirect exports toward alternative buyers in response to price or policy changes in the primary market, which is a structural feature of the sector distinct from, but related to, the broader trade concentration issue.
What would change it
Meaningful diversification of the Canadian export base requires export infrastructure oriented toward other markets, including port capacity capable of handling greater volumes, pipeline routing to tidewater that would allow energy exports to reach non-US buyers, and trade agreements with enforcement mechanisms robust enough to give exporters confidence to invest in new customer relationships and supply chains outside North America. Each of these requires long lead times and substantial capital investment, and each has, in various forms, been discussed as policy over the past two decades without producing a large shift in the underlying export concentration figures. That track record is itself informative: an investor should treat announcements of new diversification initiatives as multi-year propositions rather than developments that will show up quickly in trade balance data.
How markets have historically priced this risk
Because the underlying concentration has been stable for a long period, the market has tended to underprice the risk between episodes of active trade tension and to reprice it sharply once a specific policy proposal or measure is announced. That pattern of episodic repricing, rather than a steady, continuously priced-in risk premium, is a useful thing for an investor in trade-exposed sectors to recognize, because it means the relevant catalysts are political and policy announcements specifically, not gradual shifts in the underlying trade data itself.
What to watch
Track monthly merchandise trade balance data broken out by destination and by sector, particularly the energy, automotive and forest products categories; any US tariff, content-requirement or border-measure proposals and their specific sectoral scope; progress, or lack of it, on port and pipeline infrastructure projects aimed at export diversification; and the status of trade agreement negotiations or renewals affecting the terms of Canada-US trade specifically.
Disclosure
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
Read next
 MacroHow Canada's Uranium Gets Priced Years Before It Is MinedCanada produces about a quarter of the world's uranium and exports nine-tenths of it, almost all under long-term contracts. Cameco's third quarter of 2026 shows how those contracts work: a realized price well below the spot quote, a narrowed forecast after a longer Key Lake shutdown, and a contract book that ties future prices to the market inside floors and ceilings.Daniel Okoye · October 31, 2026 · 6 min
 MacroCanada's Economy Was Flat in August, and the Loonie Ended October FirmerReal gross domestic product was essentially unchanged in August 2026, Statistics Canada said on October 30, 2026, the second flat month in a row, and was 1.5 per cent higher than in August 2025. An advance estimate shows a 0.1 per cent decline in September, which the agency said leaves third-quarter growth at 0.3 per cent. The Canadian dollar was worth US$0.7163 on October 30 by the Bank of Canada's daily average, up from its 2026 low of US$0.7007 on October 9, and the 2-year and 10-year Government of Canada benchmark yields were 3.36 and 3.84 per cent on October 29.Marc Belzile · October 31, 2026 · 8 min
 Mining & EnergyIvanhoe Mines Reports Tuesday on a 76,401-Tonne Copper QuarterIvanhoe Mines publishes its third-quarter 2026 financial results after the market closes on November 3 and holds its call on November 4. The production is already public: 76,401 tonnes of copper from Kamoa-Kakula, a record 77,147 tonnes of zinc from Kipushi, and guidance held. The results add the earnings, costs and balance sheet behind those tonnes, with the shares at C$9.00 at the November 2 close.Élise Galarneau · November 3, 2026 · 6 min
Get the Maple Morning Debrief
Yesterday's close, overnight, and what to watch before the open — in your inbox by 6 a.m. ET. Free, and one click to unsubscribe.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Sources and references (3)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Élise Galarneau (June 29, 2026). Canada's Trade Balance and the Concentration Problem. The Maple Markets. https://themaplemarkets.ca/en/newsroom/canada-s-trade-balance-and-the-concentration-problemhttps://themaplemarkets.ca/en/newsroom/canada-s-trade-balance-and-the-concentration-problem