
Stella-Jones, Infrastructure Spending and the Utility Pole Cycle
Stella-Jones sits at the intersection of grid hardening, rail capital cycles and housing activity, but its three segments respond to very different drivers. This piece breaks down why utility poles are the stable core, why railway ties add the cyclicality, and why the residential segment is the wildcard investors should watch separately.
By Hannah Kuan3 min readTranslation: human
Cet article n'est offert qu'en anglais pour le moment.
Stable segment
Utility poles
Maintenance driven
Cyclical segment
Railway ties
Freight linked
Volatile segment
Residential lumber
Being de-emphasised
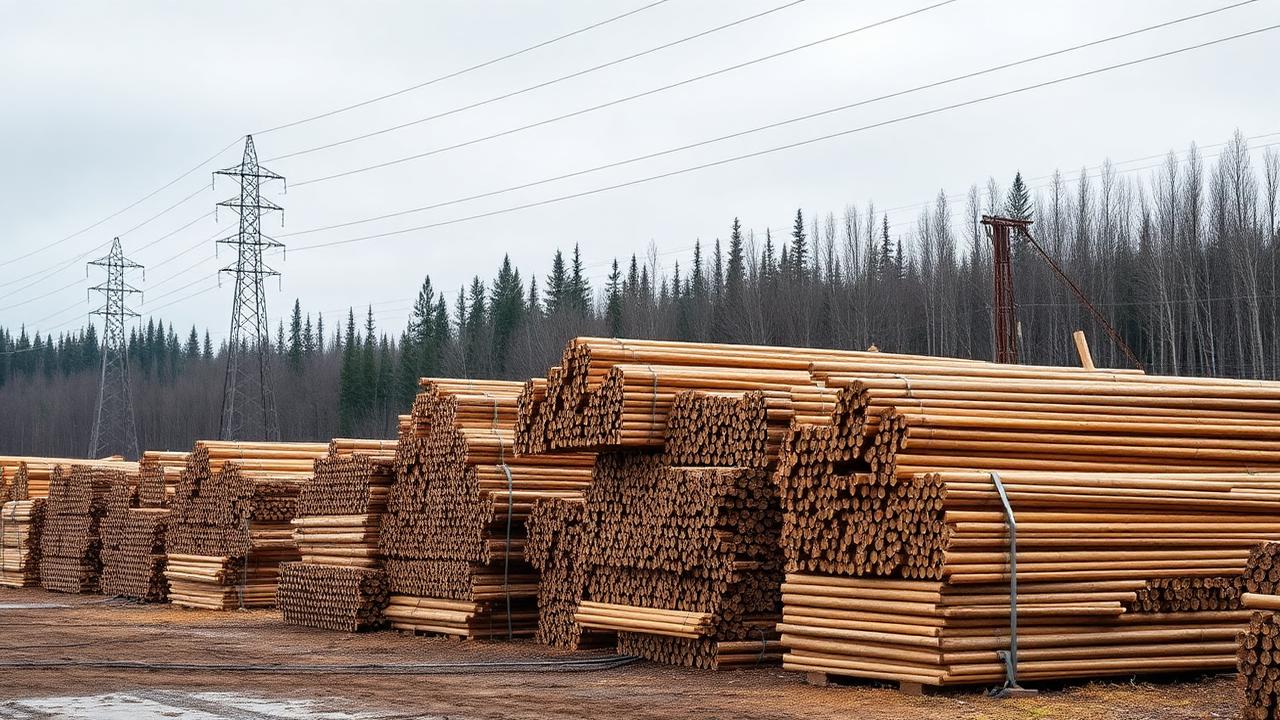
Stella-Jones manufactures pressure-treated wood products — utility poles, railway ties and residential lumber — which places it directly in the path of North American grid and rail investment. The business is less exciting than the infrastructure narrative around it, and that is the point: it sells maintenance, not novelty.
Why poles are a good business
Utility poles are replaced on a maintenance cycle regardless of the economy, and grid hardening against extreme weather has increased replacement rates. A pole that fails in a storm is a liability and a reliability problem for the utility that owns it, which makes replacement a scheduled, budgeted expense rather than a discretionary one. Freight costs relative to product value limit competition to regional suppliers, which supports pricing. A treated pole is heavy, low-value-per-tonne, and expensive to ship long distances, so plants effectively serve a regional catchment. That geographic moat is the reason margins in this segment have historically been more stable than the group headline suggests.
The railway tie cycle
Class I railroad capital budgets drive tie demand and move with freight volumes. When freight volumes soften, railroads can defer non-safety-critical tie replacement for a period without immediate consequence, which makes this segment more discretionary than utility poles on a multi-quarter view. This segment is more cyclical than utility poles and introduces most of the variance in results. Investors trying to read a quarter should separate the two: a soft print driven by rail timing is a different signal than one driven by weakening pole demand, and the two segments do not always move together.
Residential lumber is the wildcard
The residential segment tracks housing activity and lumber prices, both volatile. Housing starts and renovation spending are cyclical in a way the utility and rail businesses are not, and lumber commodity pricing adds a second layer of variability that has nothing to do with underlying demand. Management has been reducing its relative weight, which if sustained makes the overall business more predictable. A smaller residential segment means quarterly results should increasingly reflect the two more stable, contracted-style businesses rather than a commodity-lumber swing factor.
How to read segment disclosure
Because the three businesses respond to different drivers on different timelines, the useful exercise is to track segment revenue and margin separately rather than relying on the consolidated top line. A consolidated beat or miss can mask an offsetting move — strong pole demand covering a soft tie quarter, for instance — and investors who only watch the headline number risk misreading the trend in any one segment. Currency also matters here: a meaningful share of revenue is generated in US dollars, so reported results carry a translation effect that is separate from underlying volume and pricing.
Capital allocation and pricing power
Because much of the demand is non-discretionary, the company has historically had more latitude to pass through input cost inflation, particularly for treated wood chemicals and the underlying timber, than a purely consumer-facing lumber business would. That pricing power is worth distinguishing from volume growth: a period of flat volumes with rising price realisation is a different, and generally more durable, story than one where growth is coming entirely from price.
What to watch
Track segment-level revenue and margin for utility poles, railway ties and residential/other, rather than the consolidated figures alone. Watch Class I railroad capital expenditure guidance as a leading indicator for the tie business, and lumber price trends alongside US housing starts for the residential segment. Monitor the stated mix shift away from residential lumber over successive quarters, and note the US-dollar share of revenue when assessing currency effects on reported growth.
Why the business model resists disruption
There is no obvious substitute technology threatening treated wood poles or ties at scale. Composite and steel alternatives exist for both applications, but they carry a cost premium that has kept wood the default choice for the bulk of new installation and replacement work. That gives the incumbent treating infrastructure — the network of plants and the supply relationships with utilities and railroads — a durability that is easy to overlook because the product itself is unglamorous. Barriers to entry are less about patents than about the capital cost of building competing regional treating capacity and the multi-year process of qualifying as an approved supplier to utilities and Class I railroads, both of which favour the incumbent.
Divulgation
Information only. Not investment advice. The Maple Markets does not hold positions in securities discussed.
À lire ensuite
Aussi en anglais: Stella-Jones, Infrastructure Spending and the Utility Pole Cycle
 Mining & EnergyVault Strategic au Nevada : quatre mois de travaux sur une seule propriété de tungstèneLe 3 juillet 2026, Vault Strategic Mining a renoncé à deux autres options de tungstène pour se concentrer sur War Bond, une ancienne mine de tungstène des années 1950 dans l'ouest du Nevada. Depuis, elle a déclaré des résultats d'échantillonnage de surface, réalisé un levé magnétique de 73.6 kilomètres linéaires, clôturé un placement de C$1.5 million et lancé un premier rapport technique selon le Règlement 43-101. La société n'a pas encore daté ce rapport; ses états des six mois clos le 30 novembre 2026 constituent le prochain dépôt prévu.Daniel Okoye · 4 novembre 2026 · 9 min
 Mining & EnergyQIMC prévoit un programme sismique de 126.5 kilomètres dans trois provincesQuebec Innovative Materials a terminé l'acquisition de 63.7 kilomètres linéaires de sismique dans le comté de Cumberland, en Nouvelle-Écosse, où ses travaux de gaz des sols, d'hélium, de gravimétrie et de magnétisme ainsi que l'événement gazeux du sondage DDH-26-05 se trouvent sur une même grille, aujourd'hui en traitement à Calgary. Elle a prévu 36 kilomètres au Québec et 26.8 kilomètres en Ontario avec les mêmes sous-traitants, ce qui porte la couverture réalisée et prévue à environ 126.5 kilomètres linéaires, et détenait C$14.1 millions en trésorerie au 30 juin 2026.Priya Sandhu · 3 novembre 2026 · 9 min
 TechnologyHausse de 45 pour cent pour Reklaim après un troisième trimestre rentable d'affiléeReklaim Ltd. a annoncé le 3 novembre 2026 que ses produits du trimestre clos le 30 septembre avaient presque triplé sur un an, à C$3.16 millions, et qu'elle avait réalisé un bénéfice de C$1.27 million, son troisième trimestre rentable d'affilée. L'action a clôturé à C$0.40 à la Bourse de croissance TSX, en hausse de 45 pour cent sur 1.93 million d'actions. Le trimestre a aussi vu le rachat de 5.1 millions d'actions, et la veille la société a proposé de permettre aux porteurs de C$500,000 de débentures de convertir avant l'échéance au prix existant de C$0.105, sous réserve de l'approbation de la Bourse de croissance TSX.Marc Belzile · 3 novembre 2026 · 8 min
Follow this story
Follow SJ — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Sources et références (2)
Citer cette analyse
Please attribute The Maple Markets and link to the original page.
Hannah Kuan (July 22, 2026). Stella-Jones, Infrastructure Spending and the Utility Pole Cycle. The Maple Markets. https://themaplemarkets.ca/fr/newsroom/stella-jones-infrastructure-spending-and-the-utility-pole-cyclehttps://themaplemarkets.ca/fr/newsroom/stella-jones-infrastructure-spending-and-the-utility-pole-cycle