
Cameco Stock Analysis: A Full Nuclear-Fuel-Cycle Investment
More than a uranium miner
Cameco trades as CCO on the TSX and CCJ on the NYSE. It produces uranium through McArthur River/Key Lake and Cigar Lake in Saskatchewan and holds an interest in Inkai in Kazakhstan. It also operates conversion and fuel-manufacturing businesses and owns 49% of Westinghouse. Q2 2026 adjusted EBITDA was C$391 million; cash and debt were approximately C$1.1 billion and C$1.0 billion, respectively.
By Marc Belzile2 min read
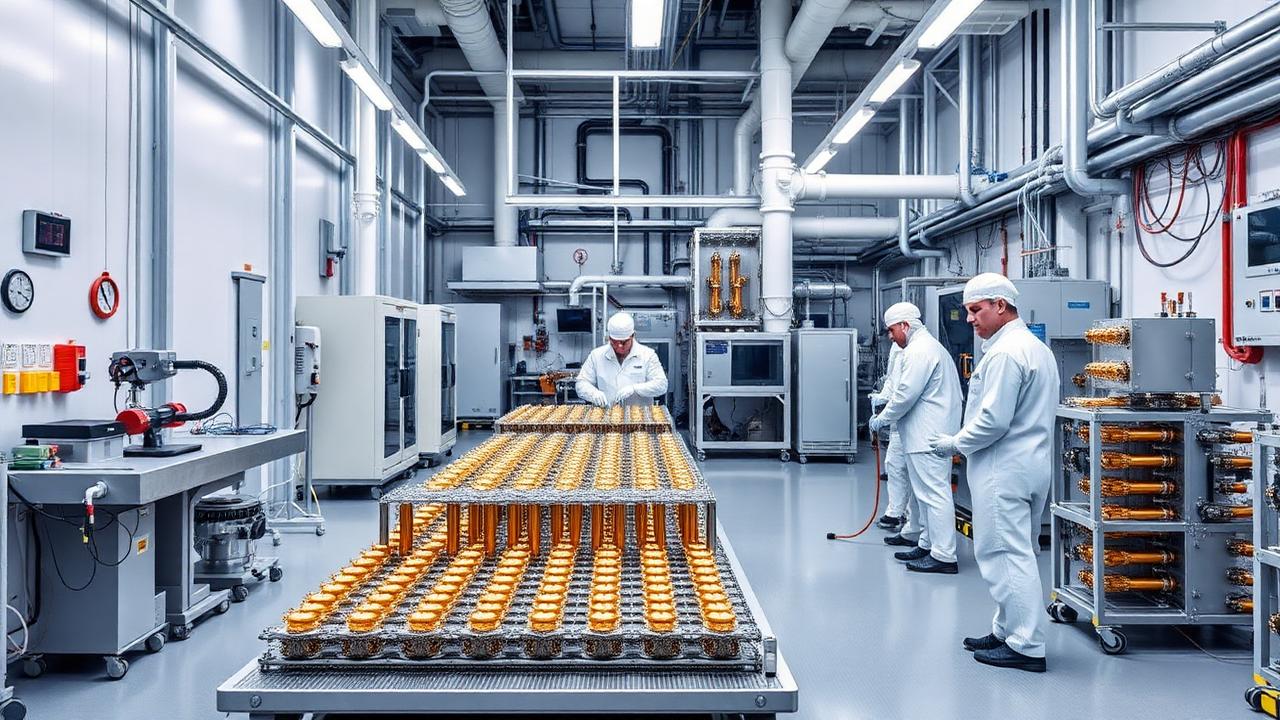
Cameco is one of the few public companies offering exposure across several stages of the nuclear-fuel and reactor-services value chain. Its core uranium assets include McArthur River/Key Lake and Cigar Lake in Saskatchewan, plus an interest in the Inkai operation in Kazakhstan. Its fuel-services segment supplies conversion and fabricated fuel products, while its 49% interest in Westinghouse adds exposure to reactor technology, services and nuclear plant life-cycle activity.
This diversified structure can reduce dependence on uranium spot prices, but it also makes quarterly results more complicated. Uranium deliveries vary by contract schedule, and Westinghouse earnings can move with the timing of major customer projects.
Latest results
For the second quarter of 2026, Cameco reported net income of C$25 million, adjusted net income of C$77 million and adjusted EBITDA of C$391 million. It held C$1.1 billion in cash, carried C$1.0 billion of debt and had an undrawn C$1.0 billion revolving facility. The company also said it had uranium contracts covering average annual deliveries of more than 28 million pounds over the following five years.
Bull case
The investment thesis rests on long-term nuclear-reactor demand, utility contracting, constrained Western uranium supply, fuel-cycle bottlenecks and growth in Westinghouse services. Long-duration contracts can provide better visibility than spot-market sales. A proposed Westinghouse public offering, for which a confidential draft registration statement was announced on July 31, 2026, could provide additional valuation transparency, though no completion is assured.
Risks
Cigar Lake and McArthur River are technically challenging underground mines. Production can be affected by ground conditions, water, milling availability and labour. Inkai creates Kazakhstan logistics and geopolitical exposure. Westinghouse adds project, legal, customer and accounting complexity. Cameco’s valuation also incorporates substantial optimism about nuclear growth, leaving the shares vulnerable if contracting slows.
Bottom line
Cameco is a broad nuclear-energy platform rather than a simple uranium-price proxy. Its contracted business and strategic assets are strengths, but investors must separate durable cash flow from quarter-to-quarter delivery and project timing.
Comparable companies
Kazatomprom, Orano and Uranium Energy.
Read next
 EnergyUranium Term Contracting: Why the Spot Price Is the Wrong NumberUranium headlines quote the spot price. Producers barely sell into it. The realised price comes from a contract book negotiated years earlier, with floors, ceilings and escalators that mute both directions.Daniel Okoye · August 26, 2026 · 7 min
 EnergyNexGen Energy After Rook I Approval: What Comes Next?NexGen trades as NXE on both the TSX and NYSE. It owns the Rook I property in Saskatchewan’s Athabasca Basin, including the Arrow uranium deposit. Rook I is a development-stage project with no operating revenue. On March 5, 2026, the Canadian Nuclear Safety Commission approved the project’s environmental assessment and Licence to Prepare Site and Construct. Q1 cash was approximately C$655 million, while reported current liabilities included significant convertible obligations.Marc Belzile · August 8, 2026 · 3 min
 EnergyThe Pressure Event Is the Result: Reading QIMC's 30.0% Hydrogen Update at Bennett HillQuébec Innovative Materials Corp. (CSE: QIMC) reported a record 30.0% H2 field reading at 413 metres in DDH-26-05 — then reported free gas reaching surface under apparent pressure between 413 and 416 metres, triggering repeated hydrogen alarms and halting the hole. Evidence for a mobile hydrogen-bearing system has strengthened. Evidence for reservoir performance has not. Benchmarked against MAX Power's completed-interval flow test at Lawson.Daniel Okoye · September 1, 2026 · 11 min
Follow this story
Follow CCO — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Disclosure
As of the publication date, the author, editor, publisher, their immediate households and affiliated entities do not own positions in the securities discussed. The Maple Markets received no compensation from the company, its officers, investor-relations providers or financiers in connection with this article. The company was given an opportunity to identify factual errors and had no right to approve the analysis or conclusions. This article is informational only and is not investment, legal, accounting or tax advice. Mining securities are volatile and may result in a total loss of capital. See the Financial Disclaimer.
Sources and references (2)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Marc Belzile (August 7, 2026). Cameco Stock Analysis: A Full Nuclear-Fuel-Cycle Investment. The Maple Markets. https://themaplemarkets.ca/en/newsroom/cameco-stock-analysis-a-full-nuclear-fuel-cycle-investmenthttps://themaplemarkets.ca/en/newsroom/cameco-stock-analysis-a-full-nuclear-fuel-cycle-investment