Hudbay and Mitsubishi Approve a US$2.07 Billion Copper World Mine in Arizona
The definitive feasibility study puts first copper in the second half of 2029 and initial capital about 59 per cent above the 2023 pre-feasibility figure, with Hudbay's own contribution deferred to 2028.
Hudbay Minerals and Mitsubishi Corporation approved construction of the Copper World mine in Pima County, Arizona, in a release dated October 21, 2026. The definitive feasibility study puts initial growth capital at US$2.07 billion in 2026 dollars, output at 102,000 tonnes of copper a year over the first decade and first production in the second half of 2029. Mitsubishi's equity, a Wheaton stream deposit and project debt come first; Hudbay's own contribution is deferred to 2028. The capital figure is about 59 per cent above the 2023 study, on the desk's arithmetic, for a mine of changed scope.
By Priya Sandhu10 min read
Initial growth capital
US$2.07 billion
in 2026 dollars; US$1.84 billion net of the Wheaton stream deposit (Hudbay release, October 21, 2026)
Copper output, years one to ten
102,000 tonnes a year
Base Case average; 15-year mine life on reserves of 390 million tonnes at 0.47 per cent copper (Hudbay release, October 21, 2026)
After-tax NPV at 8 per cent
US$1.2 billion
Base Case at US$5.00/lb copper, 17 per cent IRR, 5.4-year payback (Hudbay release, October 21, 2026)
Capital against the 2023 study
up about 59 per cent
US$2.07 billion versus about US$1.3 billion in the September 2023 pre-feasibility study; The Maple Markets' arithmetic on Hudbay's two documents, different mine scope
HBM close, Toronto
C$33.71
up 1.32 per cent on 2,619,366 shares, October 21, 2026, per end-of-day data read at 15:17 Pacific (TMX Money); German line WKN A0DPL4, ISIN CA4436281022, Frankfurt symbol OCKA (Deutsche Börse)
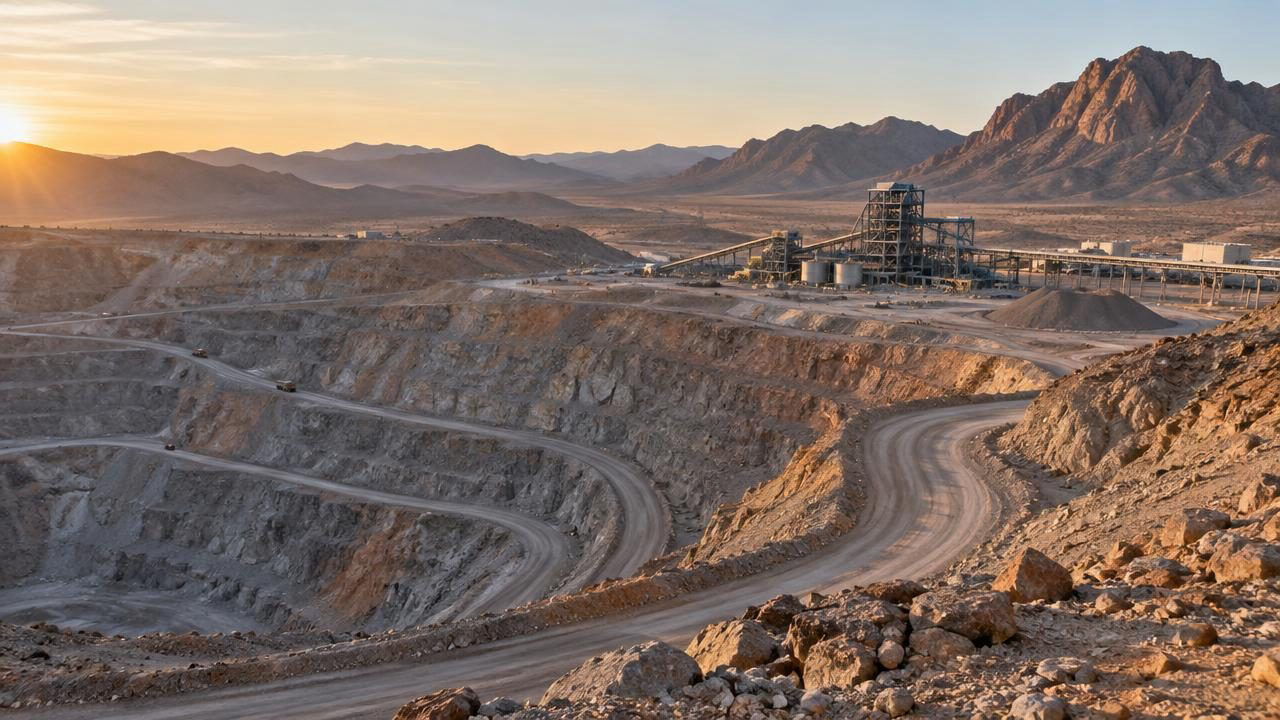
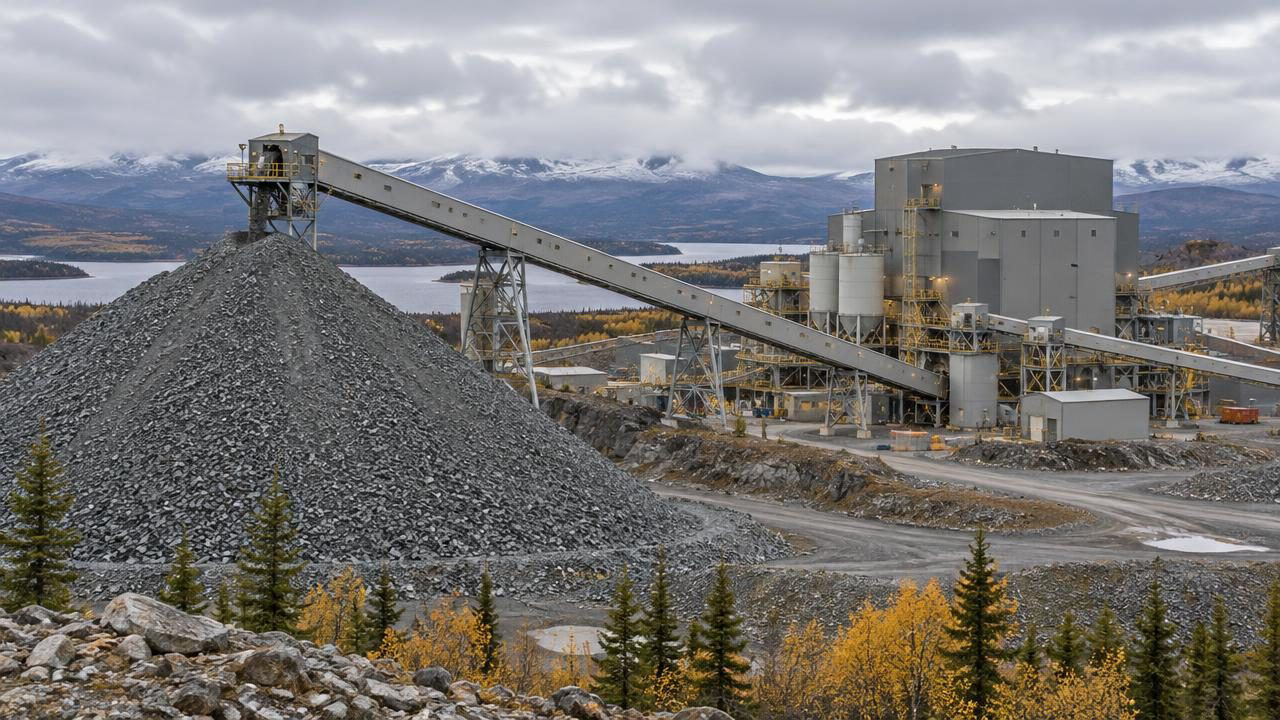
Pima County, in the dry country south of Tucson, Arizona, is where Hudbay Minerals and Mitsubishi Corporation will spend the next three years building a copper mine. The two companies approved construction of Copper World in a release dated October 21, 2026, on the strength of a definitive feasibility study, and set first production for the second half of 2029.
A final investment decision is the point at which a mining company stops studying a deposit and commits the money to build on it. Hudbay owns 70 per cent of the Copper World joint venture and Mitsubishi 30 per cent, and the release describes the decision as a joint one. The study behind it is a definitive feasibility study, the most detailed level of engineering a mine is costed to before construction. It replaces the pre-feasibility study Hudbay published in September 2023, which carried a wider margin of error and a smaller budget.
Hudbay describes itself in the release as a copper-focused critical minerals mining company with three operating mines, Constancia in Peru, Snow Lake in Manitoba and Copper Mountain in British Columbia. Copper World would be its first in the United States. Chief executive officer Peter Kukielski called the approval "a significant milestone for Hudbay"; Taro Abe, the Mitsubishi executive quoted in the release, called it "the beginning of a new phase for the joint venture".
Kukielski's reasons, in the October 21, 2026 release, were scale and a fourth mine. The project "adds more than 100,000 tonnes of annual copper production over the first 10 years", he said, and "adds a fourth operating asset to our diversified operating platform". The release puts Hudbay's consolidated annual copper production at approximately 250,000 tonnes once Copper World is producing, "doubling current production levels".
A US$2.07 billion budget, in 2026 dollars
The initial growth capital is US$2.07 billion, stated in 2026 dollars. Netting off the deposit from Wheaton Precious Metals' gold-and-silver stream brings the figure to US$1.84 billion, which is the amount the joint venture has to find from its partners and from lenders.
About US$200 million of the budget reflects scope changes since the 2023 study, Hudbay said in the October 21, 2026 release, mainly the groundwork for a larger concentrator. A concentrator is the plant that grinds ore and floats the copper minerals out of it into a concentrate that smelters buy. Copper World's starts at 60,000 short tons a day and is designed to expand to 90,000 in year five.
The mine is an open pit on proven and probable reserves of 390 million tonnes grading 0.47 per cent copper, effective August 1, 2026, and it will produce a copper concentrate and a molybdenum concentrate.
Hudbay puts the capital intensity at about US$22,600 for each tonne of annual copper production, measured on the average output of years five to twelve, with the US$242 million in-pit crushing and conveying capital and the US$443 million concentrator expansion capital counted in the capital figure, per the release. Capital intensity is the construction cost divided by the yearly output it buys.
Further spending is scheduled after start-up. A molybdenum plant costs US$25 million in year one, in-pit crushing and conveying US$242 million in year three and the concentrator expansion US$443 million in year four, per the release. In-pit crushing and conveying puts a crusher inside the pit and a conveyor belt out of it, replacing part of the haul-truck fleet and the diesel and labour that go with it.
Who pays, and in what order
Mitsubishi's US$600 million investment for 30 per cent of the joint venture closed in January 2026: US$420 million was paid at closing and the remaining US$180 million is due within eighteen months of closing, per Hudbay's March 27, 2026 release and the June 30, 2026 interim financial statements (note 5).
The October 21, 2026 release counts the full US$600 million as the venture's initial equity. It commits Mitsubishi to as much as US$423 million more in pro rata contributions, which the release defers to 2028 on the same footing as Hudbay's.
The plan dated October 21, 2026 assumes about US$650 million of project-level debt, borrowed by the joint venture against the mine's own future cash flow rather than on Hudbay's corporate balance sheet, and the release puts that at under 30 per cent leverage. Raising it would reduce Mitsubishi's further contribution to about US$218 million.
Wheaton Precious Metals' stream covers another US$230 million, due within four months of the investment decision. A further US$70 million follows five years after commercial production if the concentrator expansion goes ahead.
A precious-metals stream is a financing in which the buyer pays a deposit up front for the right to buy a share of a mine's future gold and silver at a fraction of the market price. Under the amended Copper World stream, Wheaton takes 92.5 per cent of the gold and silver and pays 15 per cent of the spot price for each ounce delivered. The study's cost figures treat the stream's deferred revenue as a by-product credit, which lowers the stated cost of producing copper.
Hudbay's own contribution is expected to total about US$500 million, under a quarter of the initial growth capital, and its first payment is deferred to 2028. The US$2.07 billion is stated net of US$127 million of anticipated equipment financing, per the release; that equipment spending is financed separately and sits outside the figure.
The company expects to pay its share from cash on hand, its credit lines and free cash flow. It reported pro forma liquidity of about US$1.3 billion at June 30, 2026, and said its revolving credit facility is being upsized to US$700 million from US$450 million and extended to November 2030, with closing expected in the fourth quarter. Net debt stood at minus 0.1 times adjusted EBITDA at June 30, 2026, meaning cash exceeded borrowings.
Two mine plans, and one of them is permitted
The study carries two cases. The Base Case runs 15 years on the proven and probable reserves, stays inside the exterior boundary of Copper World's private landholdings and needs only state and local permits. All major permits for construction and initial operations have been obtained, Hudbay stated in the release.
Copper output in the Base Case averages 102,000 tonnes a year over the first ten years. The average spans two rates the release reports separately: output runs at 84,000 tonnes a year for the first five years and 120,000 tonnes a year for the next five, after the concentrator expansion.
The Extension Case runs 37 years and takes mining onto unpatented lode and mill-site claims on federal land from year ten, which requires federal permits by then. Unpatented claims give the right to mine federal land without title to it, and the release lists the absence of challenges to their validity among the assumptions behind its forward-looking statements. Hudbay's benchmark for the federal timeline is FAST-41, a US program that puts large infrastructure projects on a published permitting schedule; the release says Arizona mining projects under it have received federal permits in about three years, and cites the program as a comparison rather than describing Copper World as admitted to it.
Hudbay estimates more than 1,000 construction jobs, 500 permanent roles and up to 3,000 indirect jobs, and US$1.1 billion in US taxes over the Base Case life. Those are company estimates, dated October 21, 2026.
The returns at US$5.00 copper
At a long-term copper price of US$5.00 a pound, the Base Case returns an after-tax net present value of US$1.2 billion and an internal rate of return of 17 per cent, with payback 5.4 years after start-up.
For scale, the COMEX copper contract for December 2026 settled at US$6.6035 a pound on October 20, 2026, per CME Group's settlements page read on the evening of October 21, 2026, so the study's long-term assumption sits below the price the exchange was clearing that week.
The net present value is calculated at an 8 per cent discount rate, which means each year's cash is marked down by that much for every year of waiting before it arrives. The internal rate of return is the discount rate at which that value falls to zero.
Both figures move with the copper price. At US$6.00 a pound the Base Case value rises to US$2.3 billion, and the Extension Case is worth US$2.5 billion at US$5.00 copper.
The release also tabulates lower and higher prices. At US$4.50 copper the Base Case value falls to US$663 million and the return to 12.9 per cent, per the copper price sensitivity table in the same release.
Cash costs over the first ten years are US$1.65 a pound of copper and sustaining cash costs US$2.22 a pound, both net of by-product credits, per the October 21, 2026 release. The cash cost is what it takes to mine and process a pound of copper and get it to market. The sustaining cash cost adds the capital spent keeping the mine running at that rate, which makes it the better measure of the margin a shareholder sees. By-product credits are the revenue from the gold, silver and molybdenum sold alongside the copper, subtracted from the cost of producing it.
Set against the 2023 study, the capital bill is up about 59 per cent
Hudbay's September 8, 2023 pre-feasibility study, as summarised in the company's third-quarter 2023 management's discussion and analysis dated November 8, 2023, put initial capital at about US$1.3 billion. The new figure of US$2.07 billion is about 59 per cent higher. That percentage is The Maple Markets' own division of one Hudbay number by the other, on Hudbay's two documents, and the two studies do not describe the same mine.
| Measure | September 2023 pre-feasibility study (Phase I) | October 2026 definitive feasibility study (Base Case) |
|---|---|---|
| Initial capital | about US$1.3 billion (US$1.1 billion net of the stream) | US$2.07 billion (US$1.84 billion net of the stream deposit) |
| Copper price assumed | US$3.75/lb | US$5.00/lb |
| Mine life | 20 years | 15 years (37 years in the Extension Case) |
| Average copper, first ten years | about 92,000 tonnes a year | 102,000 tonnes a year |
| Cash cost, first ten years | US$1.53/lb | US$1.65/lb |
| Sustaining cash cost, first ten years | US$1.95/lb | US$2.22/lb |
| After-tax NPV at 8 per cent | US$1.1 billion | US$1.2 billion (US$1,241 million) |
| After-tax IRR | 19 per cent | 17 per cent |
Read across, the capital rose by about US$770 million while the copper price the study is run at rose by US$1.25 a pound, and the after-tax value moved from US$1.1 billion to US$1.2 billion. On the company's own figures, the higher copper price assumption and the higher capital bill roughly offset each other in the valuation.
The new budget is stated in 2026 dollars and the old one was costed three years earlier. About US$200 million of the increase is scope change the company has itemised; the remaining roughly US$570 million is carried in the release without a breakdown.
The release does list the principal changes since the 2023 study: the pathway to the 90,000 tons-a-day expansion, an in-pit crushing and conveying system of 100,000 tons a day nominal capacity, conversion of about a third of the tailings to filtered tailings, and an East pit about 20 per cent smaller, without a dollar figure for each.
The mine life moved too. The 2023 Phase I ran 20 years on state and local permits; the 2026 Base Case runs 15, and the long-life plan now sits in the Extension Case, behind the federal permits. First-decade output is about 10,000 tonnes a year higher than the 2023 study carried.
One day of trading on the decision
Hudbay shares closed at C$33.71 on the Toronto Stock Exchange on October 21, 2026, up 1.32 per cent, per end-of-day data read at 15:17 Pacific on October 21, 2026 from TMX Money.
Volume was 2,619,366 shares, about 1.3 times the average daily turnover, per market data read after the close, and the exchange put the market value at about C$15.0 billion.
The close sat inside a 52-week range of C$20.26 to C$44.48.
The same share trades in New York under HBM and on the German exchanges under WKN A0DPL4 and ISIN CA4436281022, with the Frankfurt exchange listing it under the symbol OCKA, per the Deutsche Börse quote page read after the close on October 21, 2026.
The dates that follow the decision
Wheaton's US$230 million deposit is due within four months of the October 21, 2026 decision. The upsized credit facility is expected to close in the fourth quarter of 2026.
The technical report for the study, the independent engineering document Canadian securities rules require behind a feasibility study, was filed on Hudbay's SEDAR+ profile on October 21, 2026 (Technical report (NI 43-101), submitted 07:03 Eastern), with an EDGAR filing to follow per the release. Every figure above is the release's; the technical report is the document that carries the reserve and cost detail behind them.
Hudbay's third-quarter 2026 results are listed for November 12, 2026, per Hudbay's October 15, 2026 release, which sets the results before the market open and a call at 11:00 a.m. ET. They will be the first results published since the decision.
Hudbay's first cash payment into the project falls in 2028. First copper is targeted for the second half of 2029, about 36 months out.
Copper World now has a budget, a start date and a partner with US$420 million already paid in. The figure every later update will be measured against is US$2.07 billion, in 2026 dollars.
Disclosure
Transparency note. This is an independent due-diligence analysis and editorial opinion piece produced by The Maple Markets editorial desk. It is not sponsored, promoted or commissioned, and no compensation of any kind has been received from Hudbay Minerals Inc. (TSX: HBM), Mitsubishi Corporation, Wheaton Precious Metals Corp. or any party acting on their behalf. The analysis is based on public disclosure available as of the publish date; every figure is attributed to its primary source. The Maple Markets and its authors may hold positions in securities mentioned; nothing here is a recommendation to buy, sell or hold any security, and readers should not treat it as investment advice. Past disclosure does not guarantee future results. Policies: Editorial Standards · Financial Disclaimer.
Read next
 Mining and ResourcesWhy Hudbay's Snow Lake Reserves Now Run to 2043Hudbay Minerals said on 28 September 2026 that mineral reserves at its Snow Lake operations in Manitoba now support mining until 2043, an 18-year reserve life and two years longer than the January 2026 estimate. Reserves rose 7.5 million tonnes to 27.0 million tonnes holding about 2.0 million ounces of gold. The figures rest on assumed prices of US$3,600 an ounce for gold and US$5.00 a pound for copper, both below where those metals traded that day.Élise Galarneau · September 29, 2026 · 7 min
 Mining & EnergyWhy DPM Metals' Own Outlook Stops Short of a Million OuncesDPM Metals Inc. (TSX: DPM) guides to 305,000 to 365,000 gold-equivalent ounces in 2026 and publishes an outlook averaging about 350,000 a year through 2028. Adding Čoka Rakita at its feasibility-study rate gets to roughly 530,000. The chief executive's own public figure is about 600,000. The million-ounce target circulating among shareholders is an inference drawn from an interview, not guidance, and the two assets that could close the gap have no published resource estimate.Daniel Okoye · October 7, 2026 · 8 min
 MacroThree Miners Head Into the Quarter That Settles Their 2026 GuidanceProduction guidance is the forward-looking number a Toronto-listed miner is judged against all year, and Canada's disclosure rules require a reasonable basis for it and a discussion in the MD&A when events make a material miss likely. With nine months reported, Equinox Gold needs about 258,500 ounces in the fourth quarter to reach its range, Ivanhoe Mines needs about 77,900 tonnes of copper at Kamoa-Kakula, and B2Gold reports its third quarter on November 4.Daniel Okoye · October 18, 2026 · 7 min
Follow this story
Follow HBM.TO — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Sources and references (10)
- Hudbay news release, October 21, 2026: Hudbay and Mitsubishi Approve Copper World Project Construction (Form 6-K exhibit 99.1, SEC EDGAR)
- Hudbay Minerals, management's discussion and analysis for the third quarter of 2023, dated November 8, 2023, Copper World pre-feasibility study summary (Form 6-K exhibit 99.3, SEC EDGAR)
- Hudbay news release, March 27, 2026: Hudbay Provides Annual Reserve and Resource Update with Mine Life Extensions and Improved Three-Year Production Outlook (Form 6-K exhibit 99.1, SEC EDGAR; Mitsubishi closing terms)
- Hudbay Minerals, unaudited condensed consolidated interim financial statements for the three and six months ended June 30, 2026, note 5 (Form 6-K exhibit 99.1, SEC EDGAR)
- Hudbay news release, October 15, 2026: Hudbay to Host Conference Call for Third Quarter 2026 Results
- TMX Money, HBM quote page, Toronto Stock Exchange (end-of-day data read at 15:17 Pacific, October 21, 2026)
- SEDAR+, Hudbay Minerals Inc. (profile 000001691): Technical report (NI 43-101), Copper World definitive feasibility study, submitted October 21, 2026
- Deutsche Börse, Frankfurt Stock Exchange: HudBay Minerals Inc. equity page (WKN A0DPL4, ISIN CA4436281022, symbol OCKA)
- Börse Stuttgart, HudBay Minerals equity page, WKN A0DPL4
- CME Group, COMEX copper futures settlements (trade date October 20, 2026) and delayed quotes (read 8:26 p.m. Central, October 21, 2026)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Priya Sandhu (October 22, 2026). Hudbay and Mitsubishi Approve a US$2.07 Billion Copper World Mine in Arizona. The Maple Markets. https://themaplemarkets.ca/en/newsroom/hudbay-minerals-and-mitsubishi-approved-construction-of-the-copperhttps://themaplemarkets.ca/en/newsroom/hudbay-minerals-and-mitsubishi-approved-construction-of-the-copper