Magna Restarts Levack on a PEA, Not a Feasibility Study
The study behind the board's decision takes 2.1 of its 5.75 million tons from inferred resources, the lowest confidence category Canadian rules recognise, and the mine has no reserves at all.
Magna Mining's board approved restarting the Levack mine in Sudbury on 8 October 2026, on the strength of a preliminary economic assessment showing an after-tax net present value of C$227.0 million at a 7 per cent discount rate and a payback of 0.6 years. A preliminary economic assessment is the only economic study Canadian securities rules allow to include inferred resources, and about 37 per cent of this mine plan is inferred. Levack has no mineral reserves and the supporting technical report has not yet been filed.
By Priya Sandhu7 min read
After-tax net present value
C$227.0 million at a 7 per cent discount rate
Levack preliminary economic assessment released 8 October 2026, at US$5.10/lb copper, US$8.00/lb nickel and a CAD/USD rate of 1.385; the September 2026 spot-price case gives C$313.6 million.
Inferred share of the mine plan
about 37 per cent
2.1 million of 5,747,819 short tons, my calculation from the figures in the 8 October 2026 release; Levack has no mineral reserves.
Net initial funding
C$8.6 million
C$70.1 million of initial capital less C$5.6 million of refundable tax credits and C$55.9 million of pre-commercial operating cash flow, per the 8 October 2026 release; sustaining capital is C$168.0 million over 7.3 years.
Average annual payable metal
36.8 million lb copper equivalent
2028 to 2035, comprising 12.9 Mlb copper, 10.9 Mlb nickel and 21,400 oz platinum, palladium and gold, per the 8 October 2026 release.
Frankfurt identifiers
8YD / WKN A3CMTS / ISIN CA55925F1027
per Deutsche Boerse, read 9 October 2026; the German line showed no last price and no turnover.
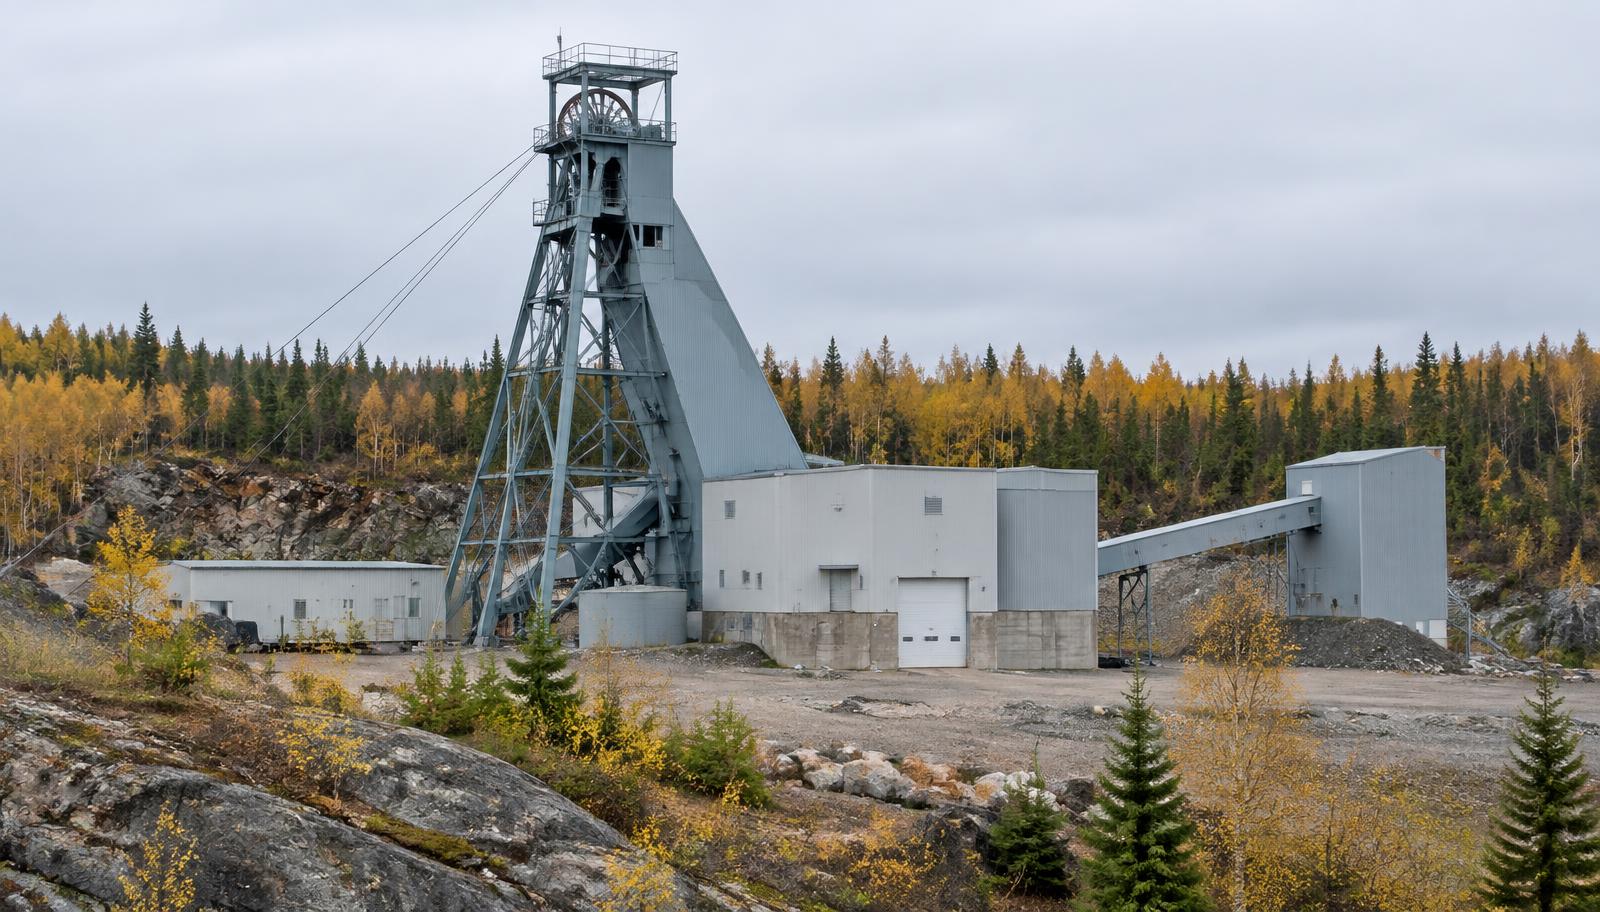
Magna Mining's board approved the restart of the Levack mine in Sudbury, Ontario on 8 October 2026, and said so in the same release that first published the study supporting it. The mine last operated in 2018. Underground development and surface construction are expected to ramp up over the coming months, with commercial production targeted for mid-2028.
The study is a preliminary economic assessment. Magna Mining Inc. (TSX: NICU) did not commission a prefeasibility or feasibility study before deciding, and the release says so in terms: the decision is not based on a feasibility study or on mineral reserves, and the company warns that production may not begin as planned or at all. That is a disclosure the company chose to make rather than one extracted from it, and it is the correct place to start.
The study is the one kind Canadian rules let you build on uncounted rock
Canadian mineral disclosure sorts tonnage by how well it is known. Measured and indicated resources have been drilled closely enough to estimate size and grade with reasonable confidence. Inferred resources have not; the geology supports an estimate, but the drill spacing does not. A mineral reserve is the narrower thing: the part of a measured or indicated resource that an engineering study has shown can be mined at a profit under stated assumptions.
A preliminary economic assessment is the only economic study the rules allow to use inferred material. A prefeasibility or feasibility study may not, which is why a reserve cannot be declared from one. The Levack study takes 5,747,819 short tons into its mine plan, of which 2.1 million tons are inferred. That is about 37 per cent of the tonnage by my own calculation from the release's figures, and it is the part of the plan that has not been drilled to the standard a reserve would need.
Levack has no mineral reserves. The release states that inferred resources are too speculative geologically for economic considerations to be applied to them that would allow their conversion to reserves, which is the standard wording and is also the point.
The economics look the way they do because the capital is small
The headline numbers are strong. The study shows an after-tax net present value of C$227.0 million at a 7 per cent discount rate, an after-tax internal rate of return of 92.4 per cent, and payback in 0.6 years. Pre-tax net present value is C$312.1 million. A spot-price case using September 2026 averages raises the after-tax figure to C$313.6 million.
The base case assumes US$5.10 per pound copper, US$8.00 per pound nickel, US$20.00 per pound cobalt, US$3,600 an ounce gold, US$1,500 an ounce platinum, US$1,200 an ounce palladium, US$45.00 an ounce silver, and a Canadian dollar at 1.385 to the US dollar. Those are the prices that produce the C$227.0 million. A return of 92 per cent is not a statement about the orebody; it is what happens when a small amount of capital meets an existing shaft.
Initial capital is C$70.1 million, spent from January 2027 to June 2028, including C$12.6 million of contingency. Against that the company applies C$5.6 million of refundable tax credits and C$55.9 million of pre-commercial operating cash flow, which is revenue from ore mined and sold during development, leaving a net initial funding requirement of C$8.6 million. Sustaining capital over the life of mine is C$168.0 million.
Those two capital numbers should be read together. The project is cheap to start and expensive to keep running, because much of the underground definition drilling and development that a conventional project pays for up front is instead funded out of cash flow as the mine goes. That shows up in the operating numbers: cash cost of US$3.23 per payable pound of copper equivalent and all-in sustaining cost of US$3.71. For comparison, Magna's own 2026 guidance for McCreedy West, issued 5 February 2026, is US$3.40 to US$3.80 per pound cash cost and US$4.20 to US$4.70 all-in sustaining, excluding stream payments. The comparison is within one company and one basin, which is the only reason it is worth making; the two mines have different ore, different infrastructure and different stream arrangements.
Life of mine is 7.3 years of commercial production at about 2,200 tons a day, at a contained head grade of 3.42 per cent copper equivalent.
The ticker says nickel, and the study says something more mixed
Copper equivalent is a presentation choice, not a description of rock. It converts every metal in the ore into the number of copper pounds that would be worth the same at a stated set of prices, so one figure can stand for several.
Average annual payable production from 2028 to 2035 is 36.8 million pounds of copper equivalent. Underneath that are 12.9 million pounds of copper, 10.9 million pounds of nickel, and 21,400 ounces of platinum, palladium and gold combined, which the release does not break out by metal.
Priced at the study's own assumptions, those nickel pounds are worth about US$87 million a year and the copper pounds about US$66 million, by my own arithmetic. Nickel is the larger contributor at these prices despite being the smaller number of pounds, because the study prices it at US$8.00 against copper's US$5.10. Anyone reading the single copper-equivalent figure as a copper number has the economics the wrong way round, and anyone reading the company's nickel ticker as the whole story has missed a third of the value sitting in copper and another slice in platinum group metals and gold.
There is no price on the German line
Magna's shares trade in Frankfurt under the symbol 8YD, with WKN A3CMTS and ISIN CA55925F1027, per Deutsche Boerse's security master read on 9 October 2026. The same page showed no last price and no turnover in units.
Price discovery for this company happens in Toronto, and on 9 October 2026 it was quiet there too. The shares closed at C$2.45, up 1.7 per cent, on 230,965 shares against a thirty-day average of 611,138, which is 0.38 times normal volume and roughly C$568,000 of turnover at the day's volume-weighted average price of C$2.46. The closing price, the volume and the average all come from QuoteMedia, delayed by 15 minutes. A study that raises the value of a company by its own measure by C$227.0 million against a market value of C$767.5 million moved the shares by four cents, which is a fact about the week rather than about the study.
What the next two filings have to carry
Two documents will settle what is currently a release and a press table.
The technical report supporting the preliminary economic assessment is to be filed within 45 days, which is on or about 22 November 2026. It will carry the qualified persons' detail behind every figure above: AGP Mining Consultants on mining and economics, through Julian Herbert, P.Eng., Rodrigo Pasqua, FAusIMM, and Gordon Zurowski, P.Eng.; Orix Geoscience on geology and the resource estimate, through Jonathan Cirelli, P.Geo.; Qualitica Consulting on sampling and analysis, through Chantal Jolette, P.Geo.; and Libertas Metallurgy on recovery, through David Middleditch.
The second is the balance sheet. Magna reported C$40.0 million of cash at the end of the second quarter of 2026 in its release of 12 August 2026, and the C$140 million strategic investment by Alpayana closed on 31 August 2026, after that quarter end. No statements covering the enlarged treasury have been published, so the cash figure that an C$8.6 million net funding requirement should be read against is not yet on file.
One other line in that August release has not been updated. It said Scott Gilbert, Chief Financial Officer, planned to retire by the end of 2026 and that Greg Huffman, Senior Vice President, Capital Markets, would take the role on his retirement. The 8 October release names Jason Jessup as Chief Executive Officer, Paul Fowler, CFA, as Executive Vice President, and David King, M.Sc., P.Geo., as Senior Vice President, Exploration and Geoscience. It names no Chief Financial Officer.
A board that owns a producing mine, a permitted shaft next door and a third-party mill can afford to decide on a preliminary study, because the cost of being wrong is development capital rather than a company. That is a real advantage and the release does not overstate it. What the study has not done is prove 2.1 million tons of the ore it plans to send through that mill.
Transparency note. This is an independent due-diligence analysis and editorial opinion piece produced by The Maple Markets editorial desk. It is not sponsored, promoted or commissioned, and no compensation of any kind has been received from Magna Mining Inc. (TSX: NICU) or any party acting on their behalf. The analysis is based on public disclosure available as of the publish date; every figure is attributed to its primary source. The Maple Markets and its authors may hold positions in securities mentioned; nothing here is a recommendation to buy, sell or hold any security, and readers should not treat it as investment advice. Past disclosure does not guarantee future results. Policies: Editorial Standards · Financial Disclaimer.
Read next
Auch auf Deutsch: Magna startet Levack auf Basis einer PEA, nicht einer Machbarkeitsstudie
 Mining and ResourcesTwo of the Three Cost Figures Circulating About Ivanhoe Mines Are Not in Its FilingsIvanhoe Mines issued no release this week, and the cost figures being traded around its shares come from memory of a conference call. One of the three checks out against the filings. The company reports C1 cash cost and does not report all-in sustaining cost at all, which makes most of the peer comparisons being drawn a comparison of two different measures. The gap between them can be priced from Ivanhoe's own capital guidance.Priya Sandhu · September 25, 2026 · 8 min
 Mining and ResourcesA Drill Can Go Onto Red Flat, and Homeland Nickel Still Has No Current ResourceHomeland Nickel Inc. told the market on 17 September 2026 that the US Forest Service had accepted its plan of operation for a sonic drill programme at Red Flat in southwest Oregon, and that it can produce updated resource estimates for Red Flat and Cleopatra without drilling a single new hole. Both are genuine steps forward. Neither is a grade. The company's own technical report says Red Flat contains no current mineral resource estimate, and the shares have gone from 7 cents to 49 cents in a year on that basis.Élise Galarneau · September 24, 2026 · 9 min
 Mining and ResourcesA US$5.22 Million Cost Share for Bitterroot's Michigan Nickel Project, and an Unnamed Matching HalfBitterroot Resources Ltd. (TSXV: BTT) said on 15 September 2026 that the U.S. Department of War will invest up to US$5,223,431 in its Michigan nickel-copper project on a 50/50 cost share basis. A cost share has two sides. The release sets out the government's side in detail and says nothing about who funds the matching half, which on the same arithmetic runs to roughly C$7.3 million against a company worth C$17.1 million at Tuesday's close.Élise Galarneau · September 15, 2026 · 7 min
Follow this story
Follow NICU.TO — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Opinion
This article expresses the author's personal views, is separate from news reporting and is not investment advice.
Disclosure
Transparency note. This is an independent due-diligence analysis and editorial opinion piece produced by The Maple Markets editorial desk. It is not sponsored, promoted or commissioned, and no compensation of any kind has been received from Magna Mining Inc. (TSX: NICU) or any party acting on their behalf. The analysis is based on public disclosure available as of the publish date; every figure is attributed to its primary source. The Maple Markets and its authors may hold positions in securities mentioned; nothing here is a recommendation to buy, sell or hold any security, and readers should not treat it as investment advice. Past disclosure does not guarantee future results. Policies: Editorial Standards · Financial Disclaimer. See the Financial Disclaimer.
Sources and references (4)
- Magna Mining Reports Results of Levack Mine Preliminary Economic Assessment and Approves Restart of Production (8 October 2026)
- Magna Mining Reports Operating and Financial Results for the Second Quarter of 2026 (12 August 2026)
- Magna Mining Announces 2026 Guidance (5 February 2026)
- Deutsche Boerse security master, MAGNA MINING INC. (8YD, WKN A3CMTS, ISIN CA55925F1027)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Priya Sandhu (October 12, 2026). Magna Restarts Levack on a PEA, Not a Feasibility Study. The Maple Markets. https://themaplemarkets.ca/en/newsroom/magna-mining-nickel-demand-is-not-nickel-price-magna-mining-s-sudburyhttps://themaplemarkets.ca/en/newsroom/magna-mining-nickel-demand-is-not-nickel-price-magna-mining-s-sudbury