
Teck Resources and Anglo Teck: Merger Upside Versus Execution Risk
Teck is becoming a larger copper-focused company
Teck’s Class A and Class B shares trade on the TSX as TECK.A and TECK.B, with TECK also listed on the NYSE. Its portfolio includes Quebrada Blanca and Carmen de Andacollo in Chile, Highland Valley Copper in British Columbia, an interest in Antamina in Peru, Red Dog in Alaska, and the Trail metallurgical complex in British Columbia. Q2 2026 revenue was C$3.61 billion and adjusted EBITDA was C$2.19 billion. Teck held C$6.05 billion in cash against C$4.81 billion of debt.
By Marc Belzile2 min read
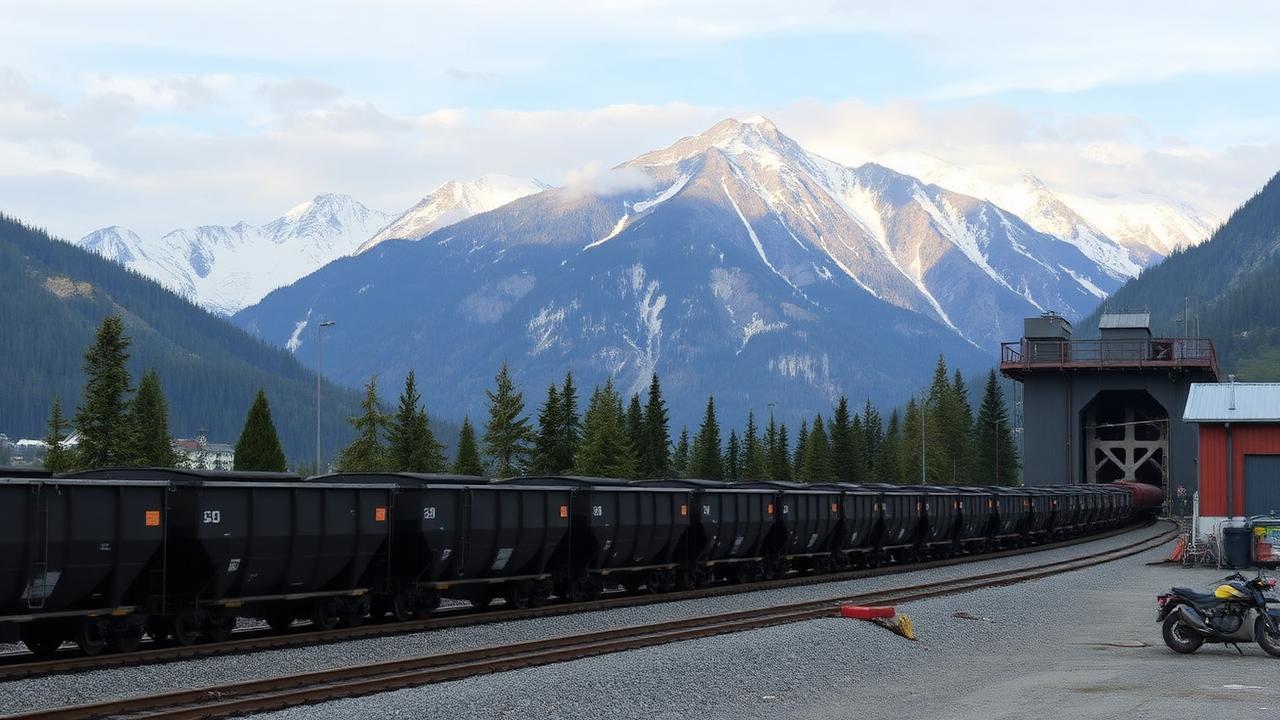
Following the sale of its steelmaking-coal business, Teck Resources is centred on copper, zinc and associated critical minerals. Its flagship copper assets include Quebrada Blanca in Chile, Highland Valley Copper in British Columbia, Carmen de Andacollo in Chile and a minority interest in Antamina in Peru. Red Dog and Trail provide significant zinc and metallurgical exposure.
Teck’s second-quarter 2026 results reflected strong commodity prices and improved operating performance. Revenue reached C$3.61 billion, adjusted EBITDA was C$2.19 billion and profit attributable to shareholders was C$854 million. Cash of C$6.05 billion exceeded total debt of C$4.81 billion.
The Anglo Teck transaction
The defining investment issue is Teck’s proposed merger of equals with Anglo American. Announced in September 2025, the transaction would create “Anglo Teck,” headquartered in Canada. Shareholders of both companies approved the merger in December 2025, and Canada granted Investment Canada Act approval, but other regulatory and customary conditions remained outstanding at the end of July 2026.
Management projects approximately US$800 million in annual pre-tax synergies, as well as longer-term benefits from coordinating Teck’s Quebrada Blanca with Anglo American’s adjacent Collahuasi interest. Those estimates are forward-looking and depend on completion, integration and operating execution.
What could drive upside
Teck could benefit from sustained copper demand, stronger Quebrada Blanca throughput and recoveries, mine-life extensions at Highland Valley and Red Dog, and greater production of germanium, gallium and antimony at Trail. A July 2026 strategic-investment agreement with Canadian government-related entities supported evaluation of the Trail expansion.
Principal risks
Quebrada Blanca remains dependent on successful tailings-management-facility work and operating stabilization. The merger creates regulatory, integration, governance and capital-allocation risk. Teck also faces high-altitude water constraints, Indigenous and community engagement, tailings obligations, closure costs, labour exposure and commodity-price cyclicality.
Bottom line
Teck offers substantial copper exposure and a strong balance sheet, but its future identity may be determined by the Anglo American transaction. Investors must evaluate both the standalone asset base and the risk that expected merger benefits take longer or cost more to realize.
Comparable companies
Anglo American, Freeport-McMoRan and Southern Copper.
Disclosure
As of the publication date, the author, editor, publisher, their immediate households and affiliated entities do not own positions in the securities discussed. The Maple Markets received no compensation from the company, its officers, investor-relations providers or financiers in connection with this article. The company was given an opportunity to identify factual errors and had no right to approve the analysis or conclusions. This article is informational only and is not investment, legal, accounting or tax advice. Mining securities are volatile and may result in a total loss of capital.
Read next
 Mining and ResourcesHomeland Nickel: A Binding Offtake With Two ConditionsHomeland Nickel Inc. (TSXV: SHL) signed a binding offtake agreement with Westwin Elements on 2026-10-01 covering about 20,000 tonnes of nickel concentrate a year from its Red Flat property in Oregon. The agreement is conditional on an updated mineral resource estimate and a preliminary economic assessment the company expects in the first half of 2027. Homeland has no current mineral resource on any of its Oregon ground, and held about C$2.39 million of cash at its most recent reported balance sheet date.Priya Sandhu · October 15, 2026 · 7 min
 Mining and ResourcesDid Anything at Ivanhoe Mines Explain a 6% Drop?Ivanhoe Mines Ltd. (TSX: IVN) closed at C$10.48 on 2026-10-14, down 6.4 per cent, on volume slightly below its average and with nothing published by the company that day. Its last release, on 2026-10-08, reported record quarterly copper and zinc output. A C$14.95 billion company moving 6 per cent on no disclosure is a setup question rather than a news story, and the next dated company item is Q3 financial results on 2026-11-03.Élise Galarneau · October 15, 2026 · 7 min
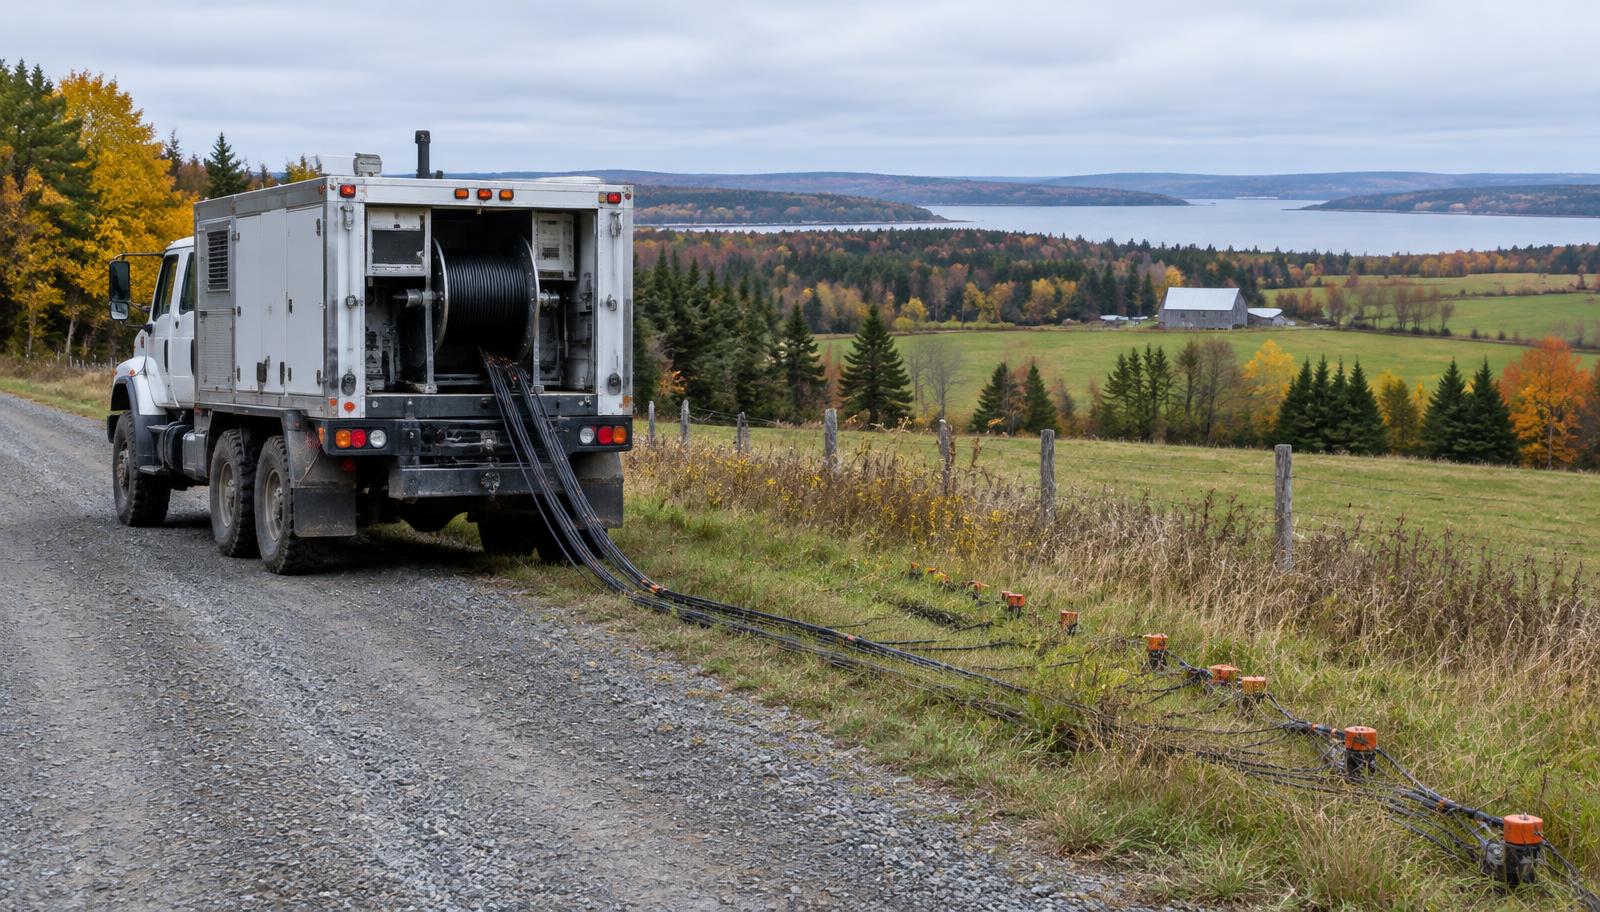 Mining and ResourcesQIMC Completes a 63.7-Kilometre Seismic Survey in Nova ScotiaQuebec Innovative Materials Corp. (CSE: QIMC) said on 14 October 2026 that it had finished acquiring 63.7 line-kilometres of 2D seismic across its Cumberland County ground in Nova Scotia, 13.7 kilometres more than planned, and the data is already with a Calgary processor. The programme was delivered ahead of plan on ground where free gas has already reached surface once, with a treasury of about C$14.84 million against liabilities of about C$1.92 million.Élise Galarneau · October 15, 2026 · 8 min
Follow this story
Follow TECK.B — the next Maple piece on this company, plus the Maple Morning Debrief before the open.
Follow and ask
Get more of our Canadian market coverage in Google Top Stories.
Sources and references (2)
Cite this analysis
Please attribute The Maple Markets and link to the original page.
Marc Belzile (August 11, 2026). Teck Resources and Anglo Teck: Merger Upside Versus Execution Risk. The Maple Markets. https://themaplemarkets.ca/en/newsroom/teck-resources-and-anglo-teck-merger-upside-versus-execution-riskhttps://themaplemarkets.ca/en/newsroom/teck-resources-and-anglo-teck-merger-upside-versus-execution-risk